

The Global Financial Crisis was a devastating era for investors.
Between January 1, 2007, and December 31, 2009, the S&P 500 plummeted by 27%.
However, during that same window, one company managed to soar by 107%.
This business relied on steady subscription revenue and offered customers a way to cut spending on all other entertainment.
Today, we are looking at a firm that would likely be the very last subscription you’d cancel during an economic downturn: Netflix.
Netflix is the undisputed king of entertainment, providing its over 325 million customers the best movies, series, and as of recently, live sporting events and video games.
In 2022, the company introduced a cheaper subscription tier mainly monetized through advertisements, and in only 3 years this revenue source already accounts for c. 4% of the company’s total revenues.
The remaining portion of the revenue comes from subscriptions paid by a highly loyal customer base with an average churn rate of 2%, indicating a high stickiness for their services.
The market is currently pricing in long-term double digit top line and bottom line growth and sustainable margins. However, assuming that Netflix trades at the same FCF yield in the future, our DCF model points to an IRR just over 10%.
Below you will find a deep dive into the business, where we cover all relevant aspects including a business overview, competitive analysis, financial review, valuation study, and my investing strategy for Netflix.
Over 20 hours of research have been invested in researching this company for you, I hope you enjoy!
Table of Contents
Introduction
Company History
Company Overview
Industry and Market Analysis
Competitive Analysis
Bull Thesis
The Compounder Score
Risks
Financials
Valuation
Concluding Thoughts (What I am personally doing)
1. Introduction
The world of entertainment has always been highly fragmented.
With customers having to choose between hundreds of platforms for streaming movies, sporting events, or playing video games.
This often results in having multiple subscriptions due to specific shows, which results in expensive monthly bills.
Netflix solves this pain point by becoming a one-stop shop, allowing users to obtain the highest value out of any possible subscription in the market.
And most recently, they fell out of the potential acquisition of Warner Bros Discovery, by not wanting to overpay for the business, proving their commitment to pursue opportunities with attractive returns.
Currently, the company has over 325 million paid subscribers, being present in over 190 countries.
This success has allowed it to reach revenues of over $45 billion with a 24% net margin in 2025.
2. Company History
1997-2006: Founding and IPO
Netflix was founded in 1997 by Reed Hastings and Marc Randolph.
Their initial vision was to build a frictionless DVD rental service, allowing customers to order DVDs online and receive them via mail.
When the website launched, customers could rent up to 925 different titles, paying $4 per movie, which heavily undercut the industry leader at the time, Blockbuster.
Hastings and Randolph were quick to realize that there was a large potential of catering to movie enthusiasts by launching a monthly subscription without late fees and without per-movie costs.
In the year 2000, the founders offered to sell Netflix to Blockbuster for $50 million, where Blockbuster famously laughed them out of the room.
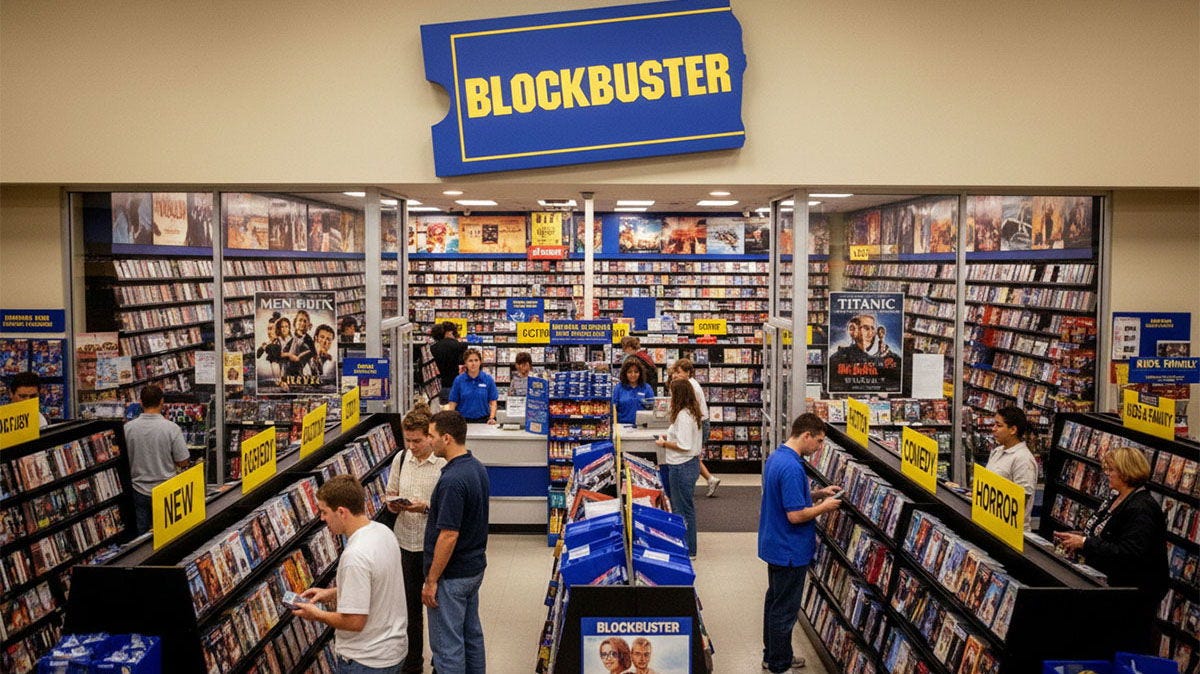
Just 2 years later, Netflix conducted its IPO and shortly after reached 1 million paid subscribers, becoming profitable for the first time in their short history.
2007-2015: Streaming and International Expansion
Netflix’s major innovation came in 2007 with the introduction of its streaming service, where subscribers could finally watch movies from their PC without the need of mailing DVDs, building the foundation for what we know as Netflix nowadays.
Immediately afterwards, Netflix partnered with Xbox, Roku, and Smart TV brands to offer its streaming services on TVs.
This streaming service offered increased scalability, allowing Netflix to begin its international expansion, entering Canada, the UK, Ireland, and the Nordic European countries.
In 2013, Netflix became a content creator, releasing its first major Originals series, House of Cards, proving that it could reduce its dependency on externally-sourced content.
2016-2025: Subscription Boom and Service Differentiation
In a single day in 2016, Netflix launches in 130 additional countries, making its services available almost everywhere in the world (except China).
In 2018, Netflix became the most-nominated studio at the Emmys, finally beating HBO and defying Hollywood.
But the real traction came with the pandemic, which caused for a massive surge in subscribers, pushing Netflix past the 200 million member mark.
Leveraging its newly-found audience, Netflix entered the Gaming world in 2021, offering mobile games to all subscribers for free, and in 2024 they signed a deal to stream WWE Raw, making its move into live sports entertainment.
In 2022, for the first time in a decade, Netflix reported a loss in subscribers, making them release their ad-supported tier and conduct their famous password sharing crackdown.
Finally, in early 2026, Netflix fell out of the deal to acquire the studio and streaming divisions of WBD, after having offered $72 billion.
2026 Onwards: Single Entertainment Destination
Netflix’s goal is clear, they want to move away from being a movie and show streaming platform to become the leader of everything related to entertainment.
After having saved cash for the potential acquisition, the company’s main focus will be investing into content development and restarting their share buyback program.
Netflix will also be also focusing on continuing its explosive ad revenue growth, creating a consistent schedule for sporting events, and shifting from downloads to Cloud-TV games.
3. Company Overview
Value Proposition
Netflix’s mission has always been about offering increased convenience and flexibility than the other offerings in the market.
Initially this translated to streamlining the DVD rental process through the integration of a website and mail deliveries, but this has since evolved into a platform were subscribers may stream on-demand content without the need for ads.
The main benefits to customers can be grouped into:
The availability of a massive library of content with over 10,000 movies and series, with video games and live streamed content.
The feasibility of watching as much content as possible whenever and however by only paying a monthly subscription.
How Netflix works
Netflix is designed to be a highly intuitive, easy to use service, catering to a wide audience.
Every time someone downloads the app, they are required to create an account and choose one of the available subscription plans.
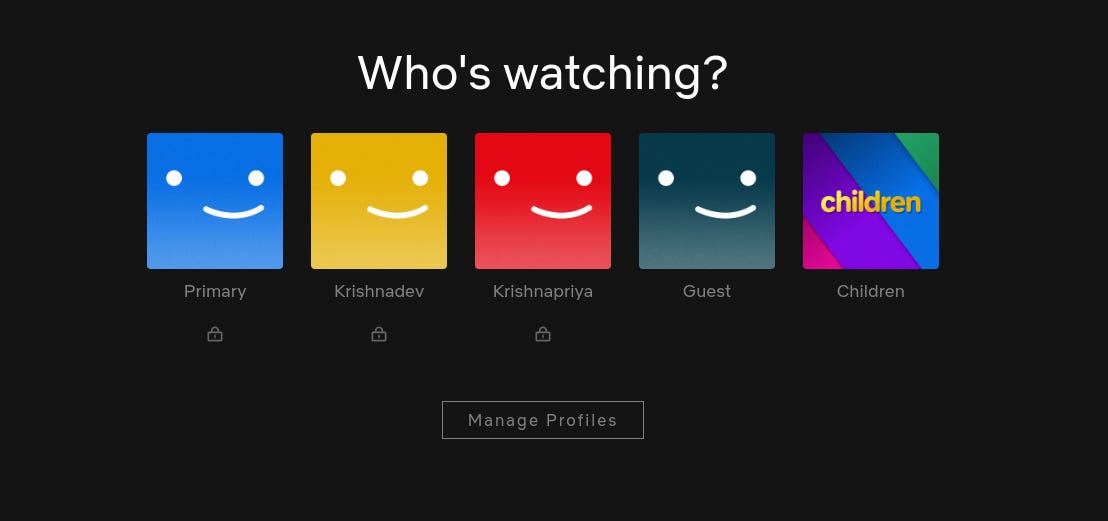
Once inside, the only setup needed is creating the required profiles, which will act as the independent personal digital libraries for each family member.
From then on, the moment you start watching, Netflix will ensure that the video starts instantly without buffering and without any actions needed from the subscriber.
Over time, as you watch more content, the algorithm will track your taste to update your homepage.
This is an incredible feature as it removes the stress of finding the next piece of content to digest by providing tailored recommendations of what to watch next.
Products and services
Netflix works under a very simple business model with all of its different offerings included in the same subscription.
This simplicity is what allows its subscribers to use its services whenever and wherever, providing the flexibility that is core to their value proposition.
Despite Netflix operating as a single business segment, we can divide its offerings into three distinct categories:
Core streaming
This is Netflix’s foundational service, allowing its subscribers to watch movies, series, and even documentaries.
It serves as the company’s primary selling point, providing the world’s largest library of professionally made, on-demand content.
On the one hand, through licensing agreements, they are able to provide a comprehensive collection of some of Hollywood’s most renowned studios.
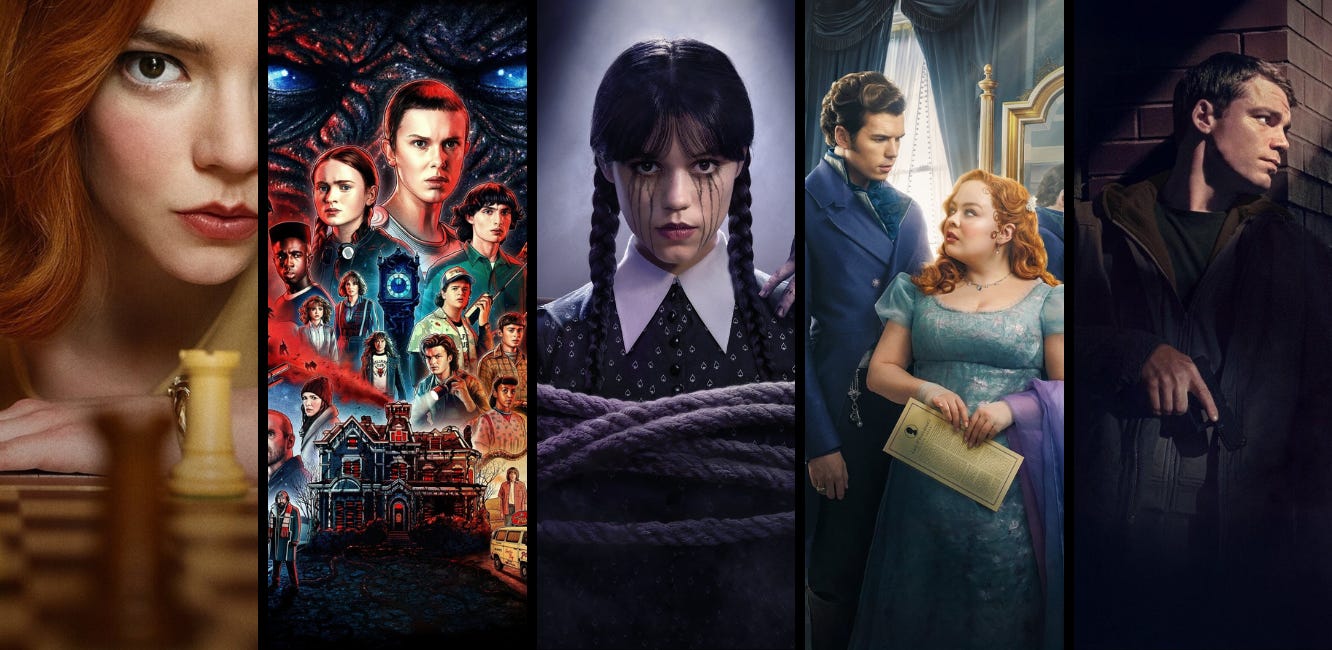
And on the other hand, they have been having an incredible success with their Originals productions, with company owned franchises like Stranger Things, Squid Games, or even Wednesday.
Netflix is moving toward hyper-personalization, attempting to generate trailers and content in real-time to match your specific mood and history (with interactive films where the viewer can decide events which will change the outcome).
Netflix games
This segment allows subscribers to download and play high-end games on their TV using their phone as a controller.
Netflix follows a similar strategy to their core streaming offering segment by mainly licensing popular titles from third-party studios to strengthen their catalog, with games like Grand Theft Auto and Football Manager 2024.
Additionally, Netflix has built several studios to create original games, mainly based on their own IPs, such as Stranger Things, and Money Heist.
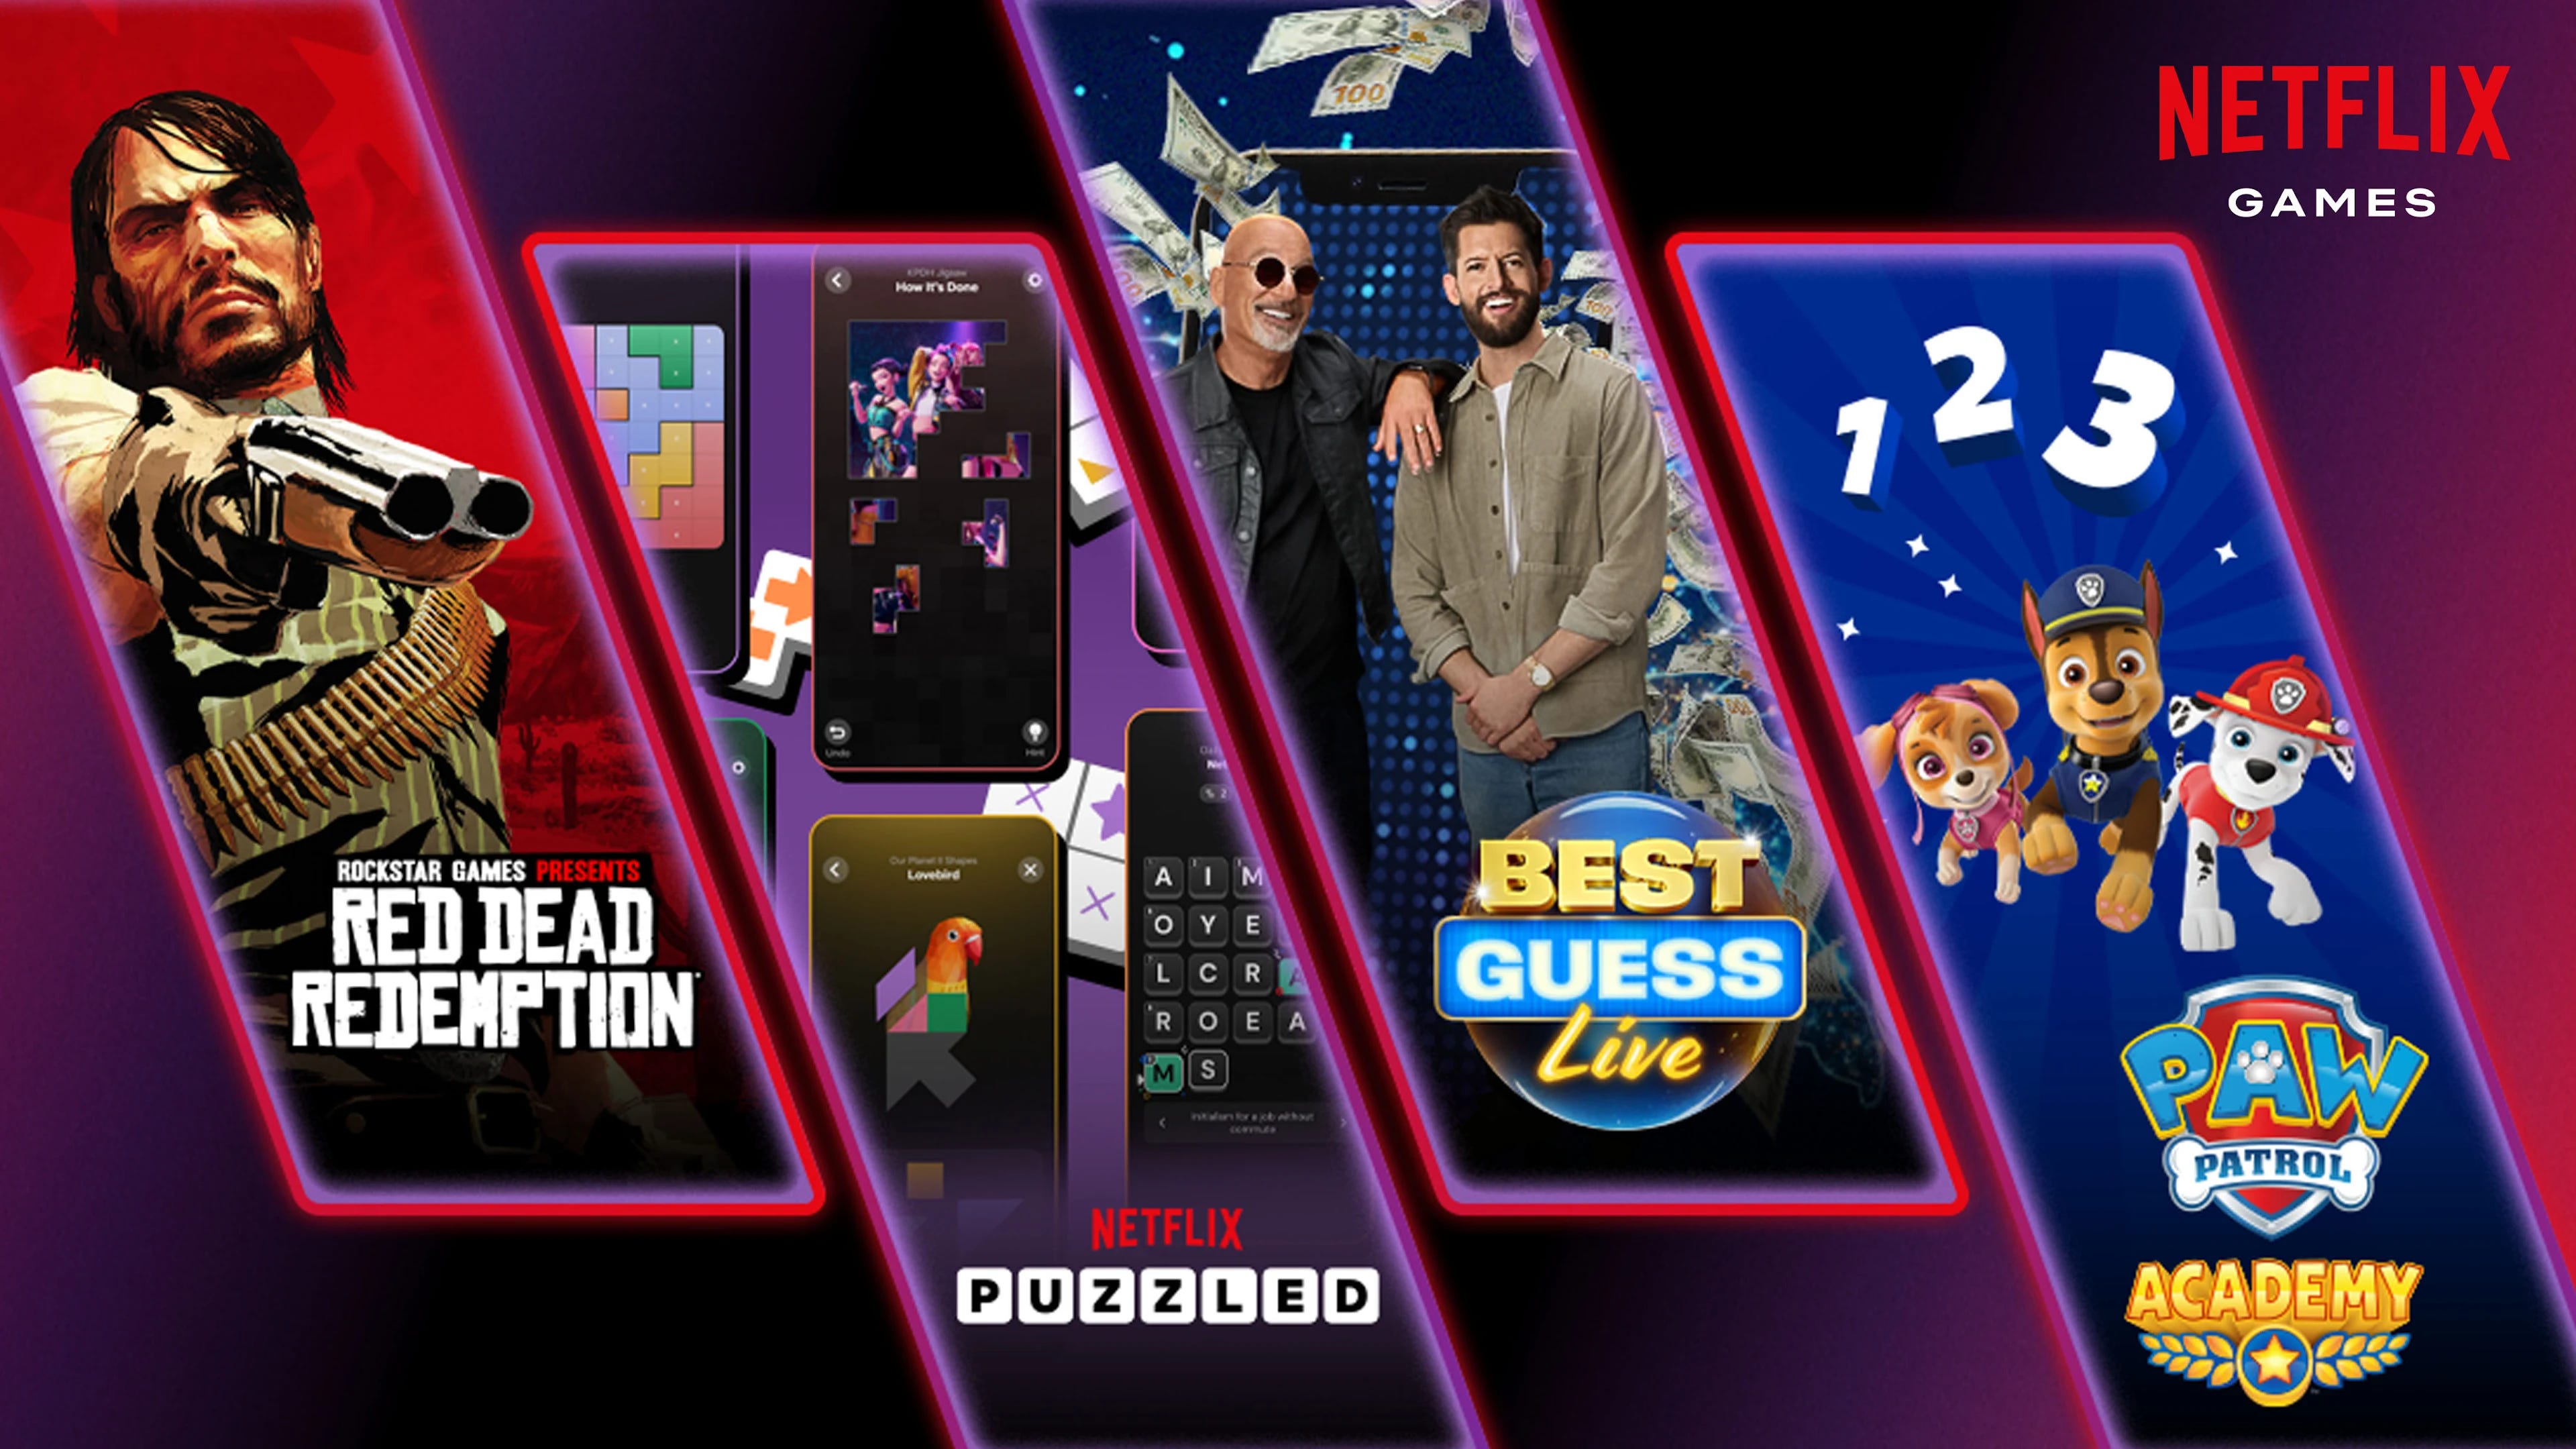
While Netflix initially aimed to build in-house high-budget games, recently their strategy has shifted towards mobile-first, IP-driven titles to reduce risk.
Despite this recent success in mobile gaming, their big focus for 2026 is cloud gaming, which will allow subscribers to play high-end games directly on the TV.
Live events and sports
This segment offers subscribers the opportunity to watch events that must be streamed live to avoid spoilers, with the initial experiments being sports events.
They are already hosting WWE Raw, NXT, and SmackDown on a weekly basis, while having streamed the NFL Christmas Day and MLB opening day games.
Netflix has also integrated video podcasts, featuring names like Bill Simmons, to test their success in this booming market.
In the future, the company aims to move from hosting sports occasionally to having a 24/7 real-time content agenda, with live news or reality competition finales where the audience can vote in real-time.
How Netflix makes money
Netflix is built around a subscription structure, allowing subscribers to choose between three different plans.
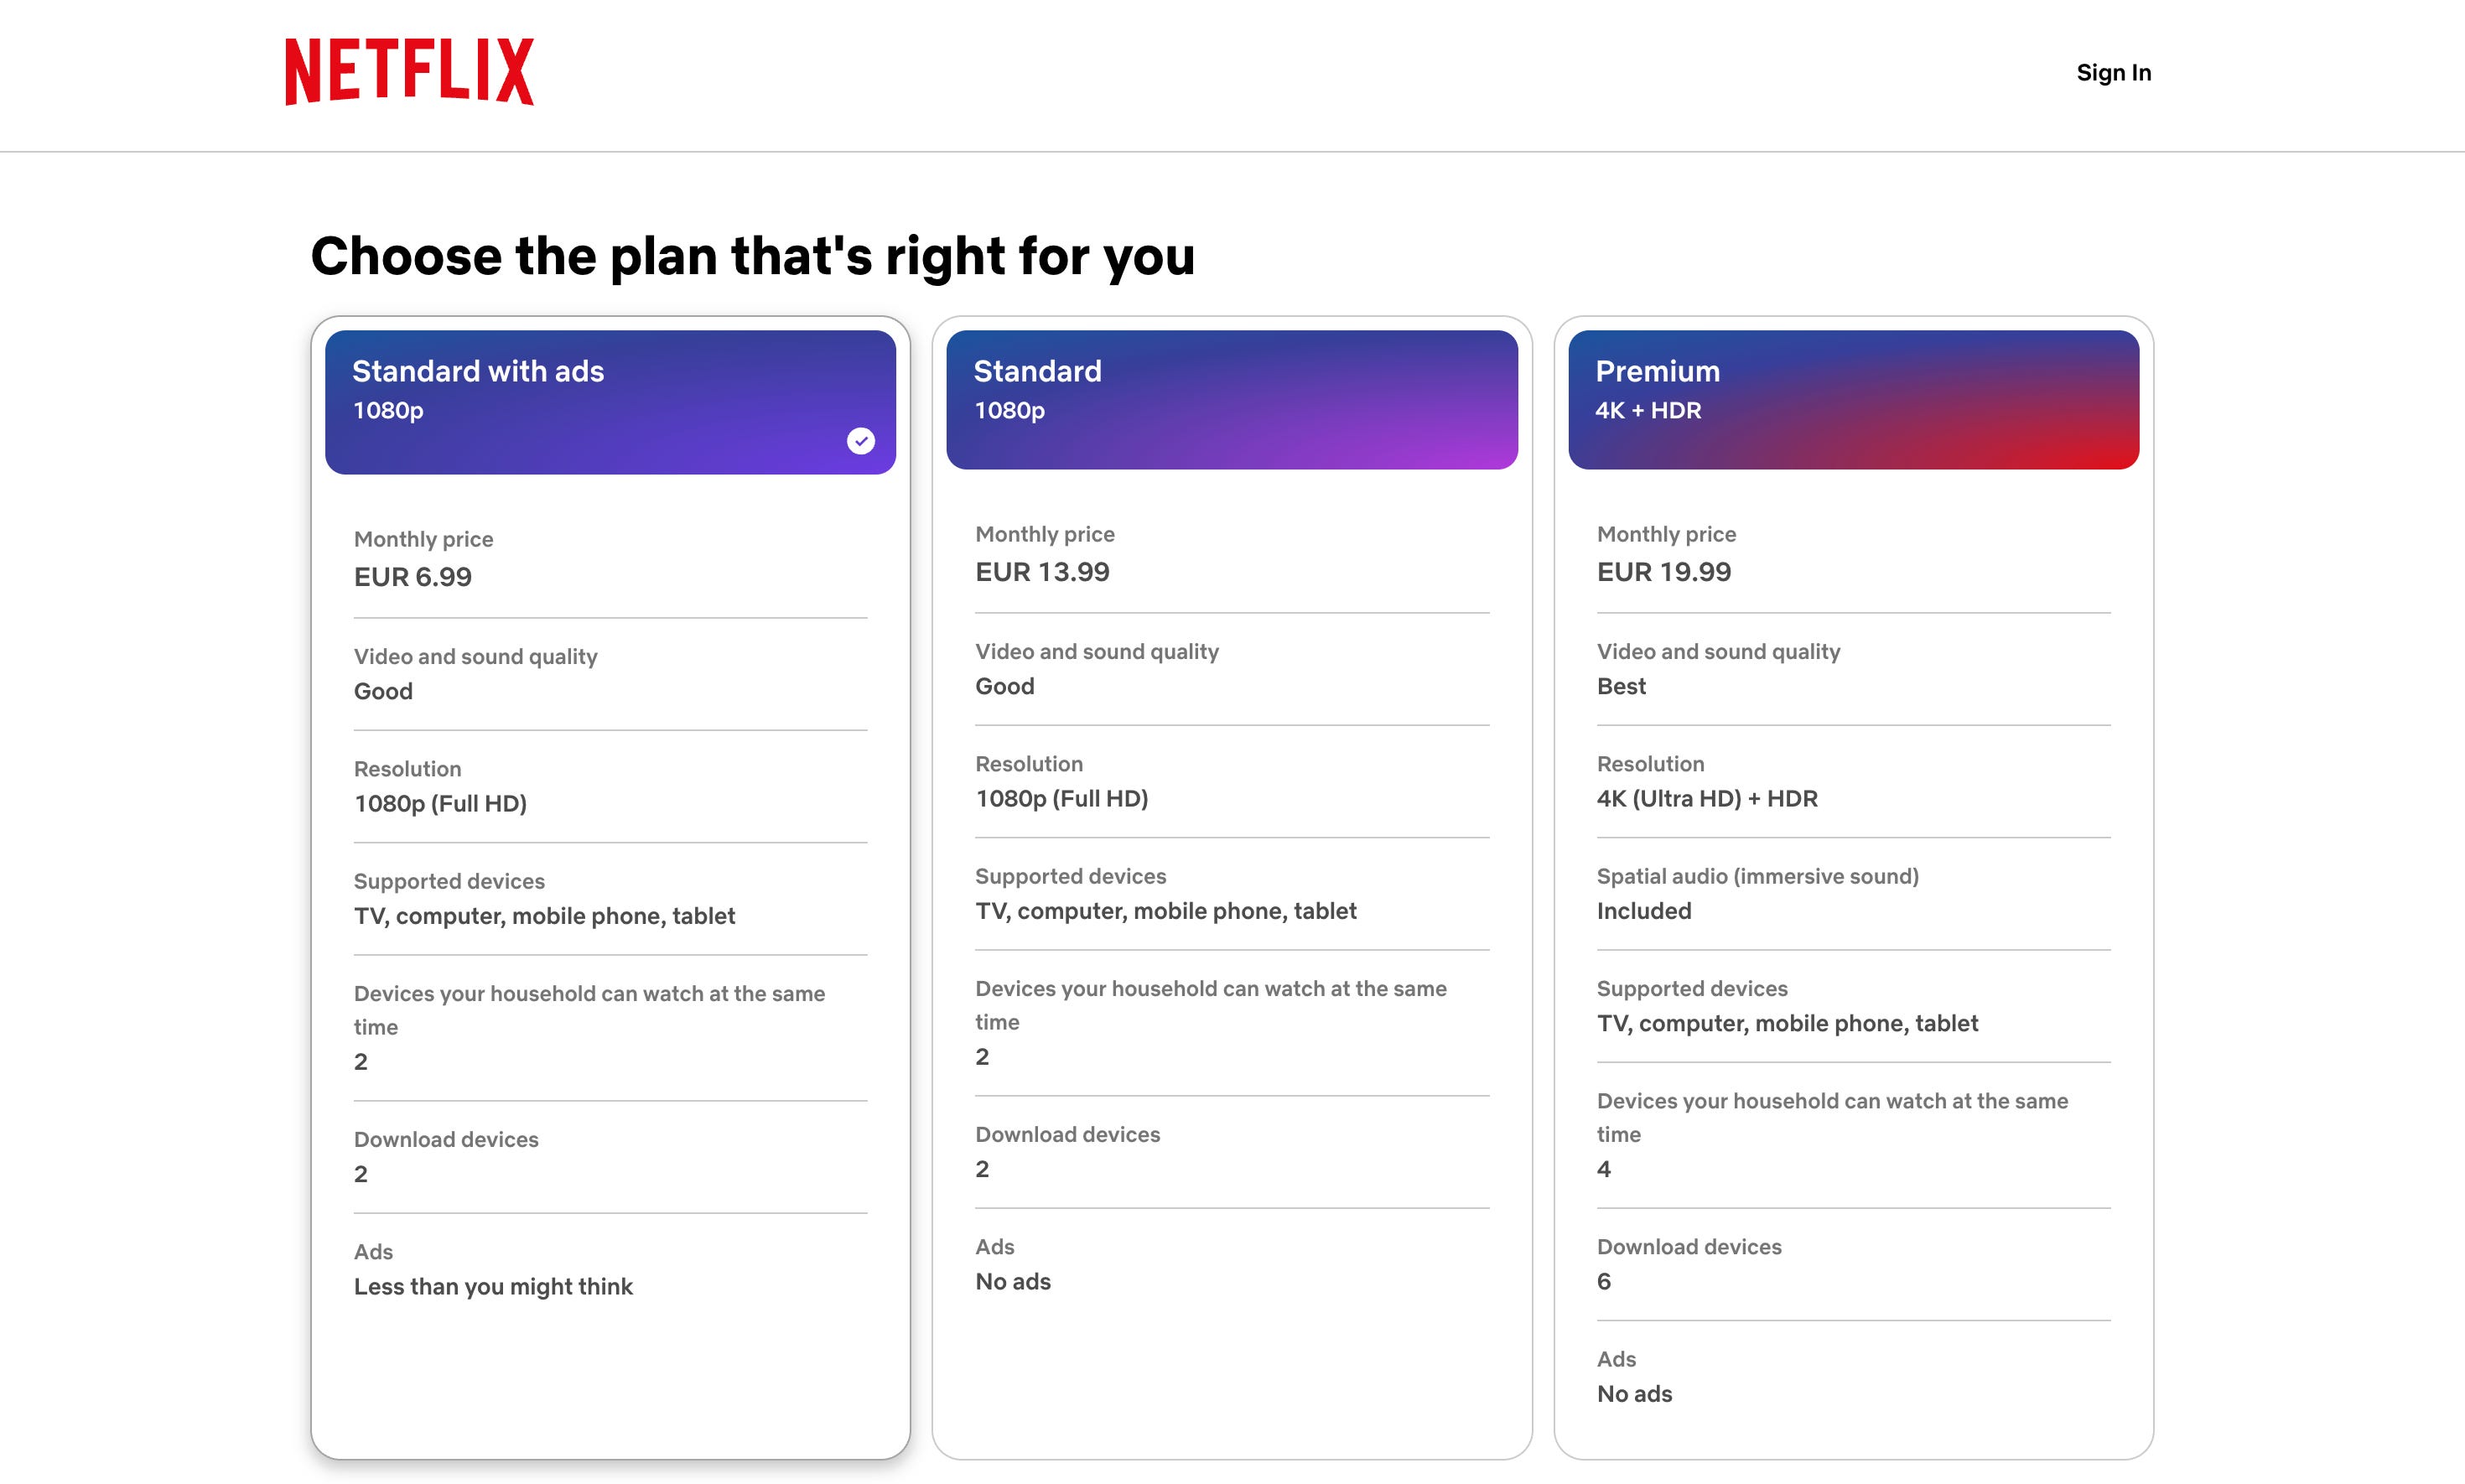
Their cheapest plan includes occasional advertisements which will interrupt your binge-watching session in a similar way to how YouTube monetizes its content.
However, this tier still allows you to have access to all of their movies, games, and live events, while allowing 2 devices to stream content at the same time per account.
The main benefit from the Standard Plan is the removal of all advertisements, allowing you to enjoy their full content library without interruptions.
Finally, their Premium Plan allows up to 4 devices to stream content at the same time per account, while including 4K resolution and spatial audio settings.
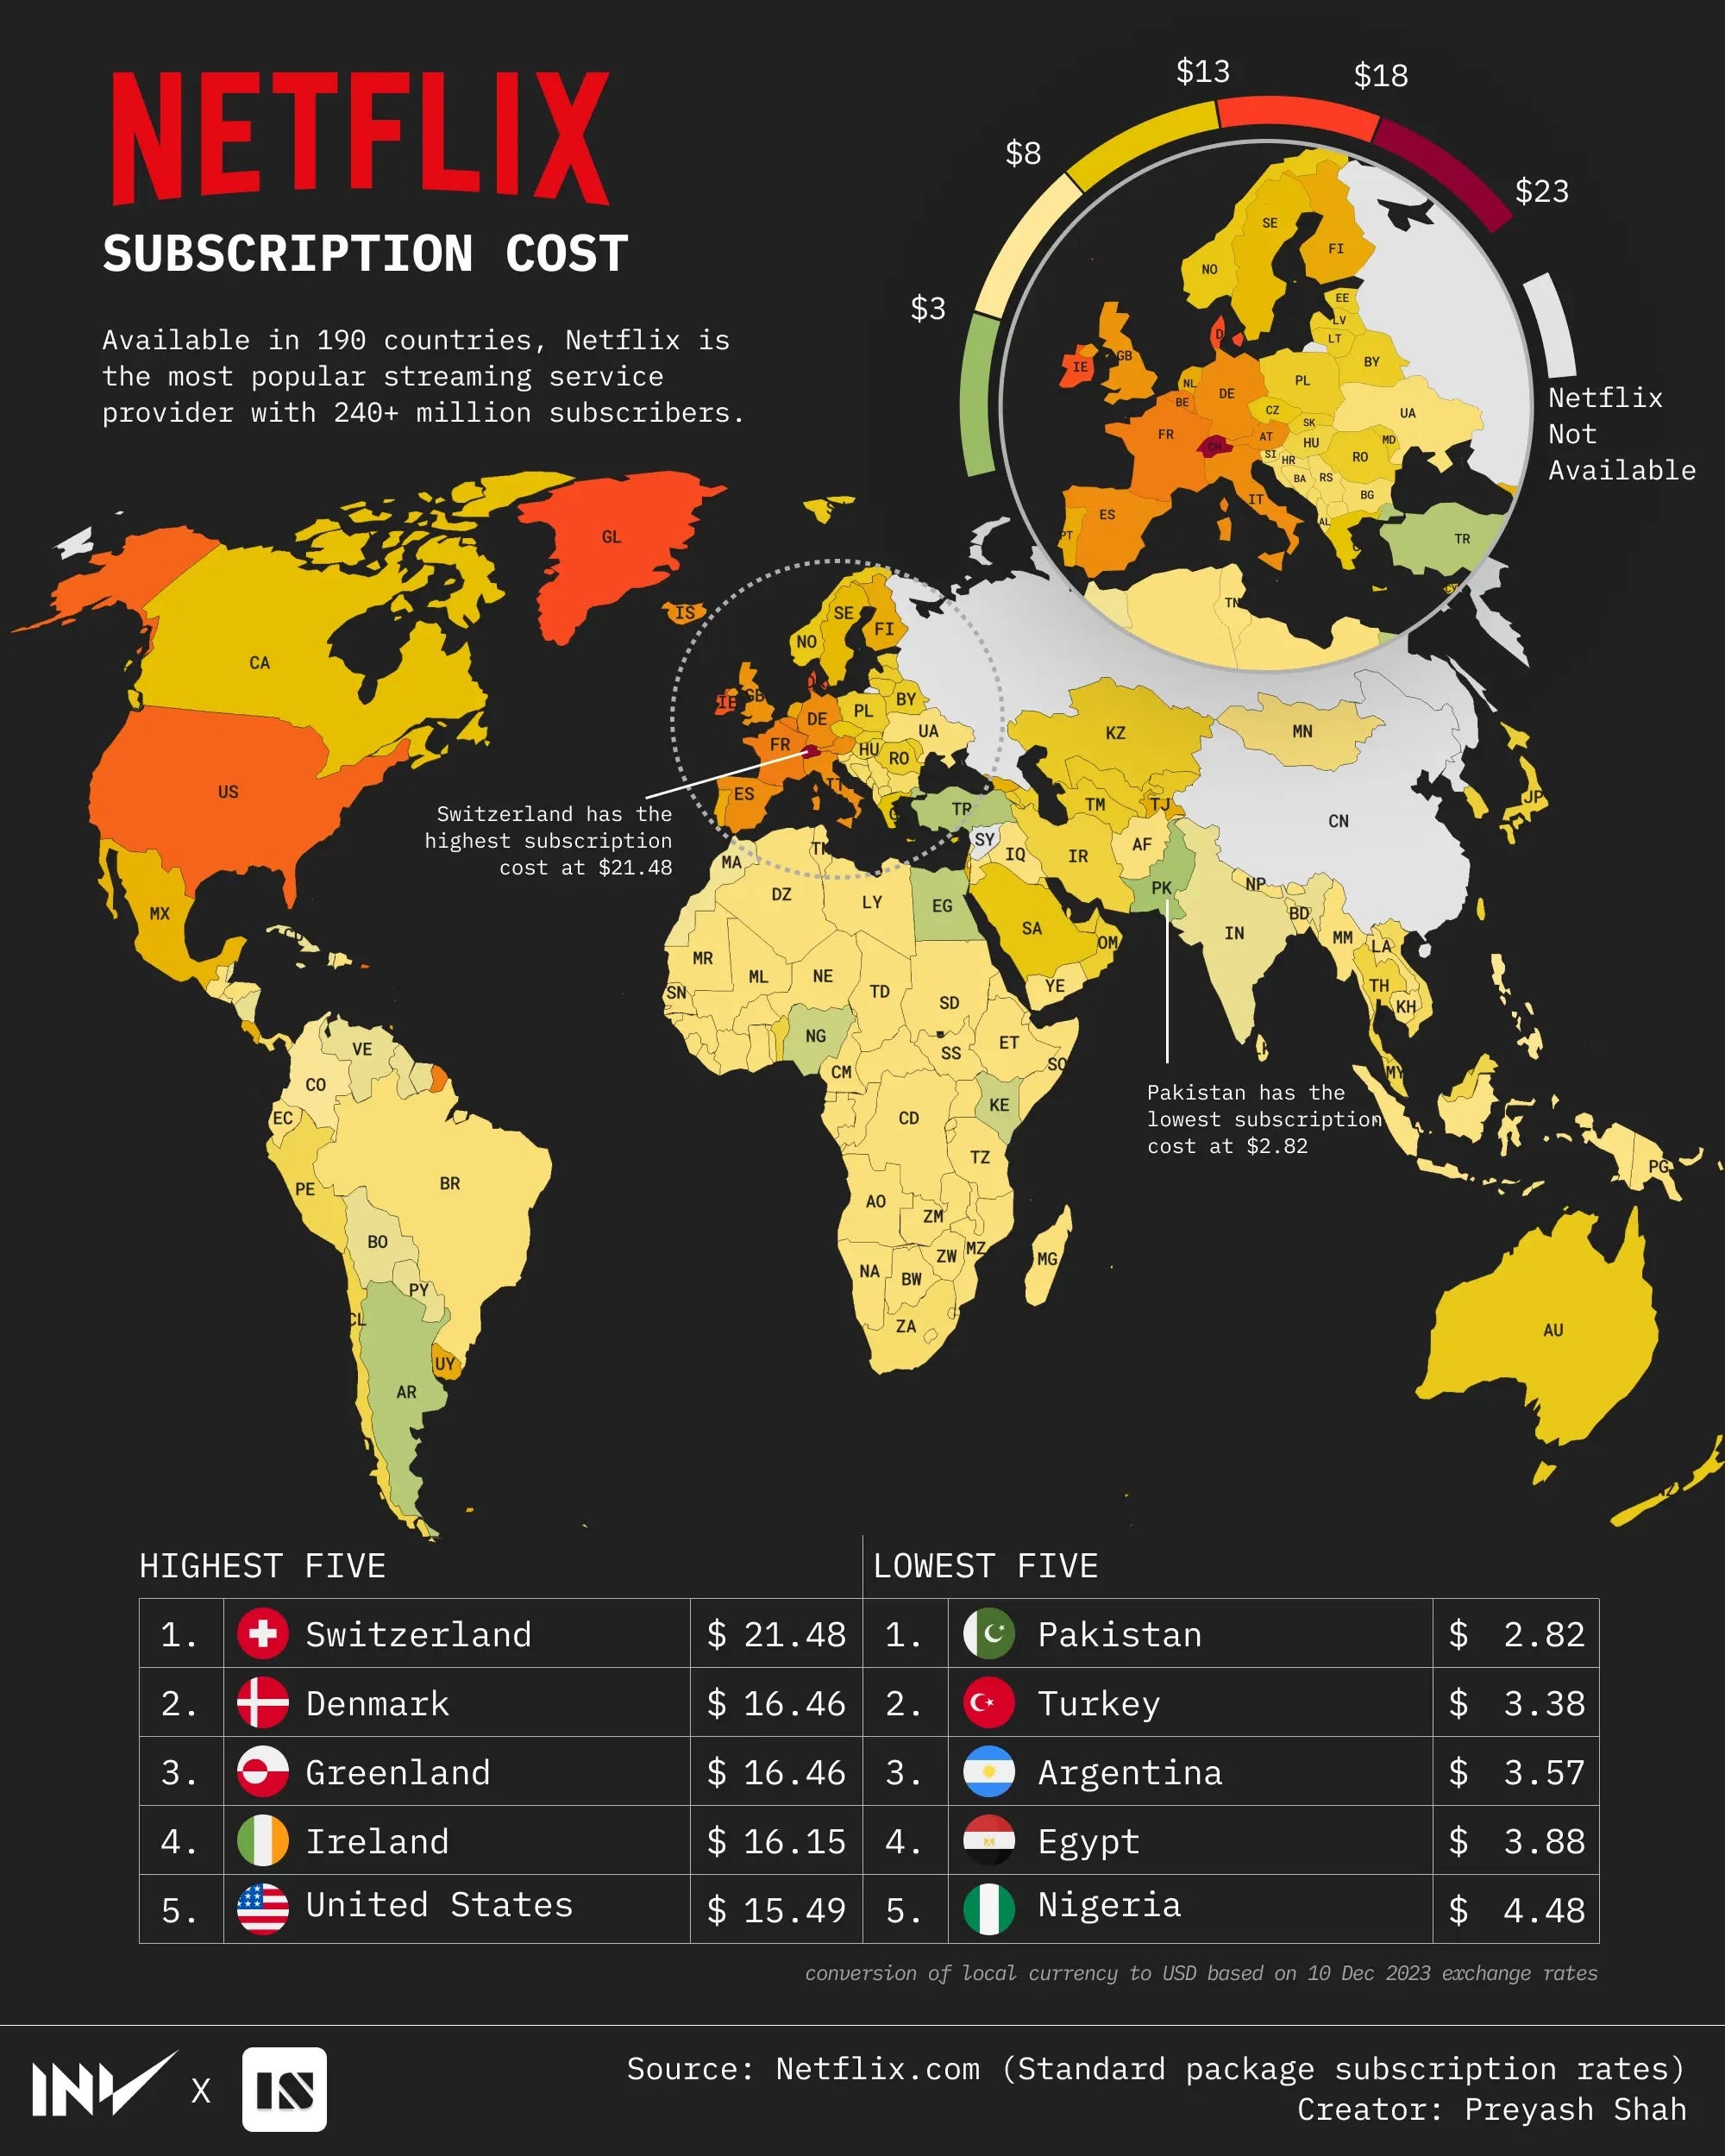
To reach a wider audience, Netflix’s subscription prices vary largely by country, with the standard plan being priced at $21/month in Switzerland and at $3/month in Pakistan in 2023.
As of October 2025, the Standard Plan with Ads had reached over 94 million monthly active users, a massive surge in comparison to the 40 million active users it had in May 2024.
It is estimated that in the countries where it is available, 40% of Netflix signups are to this tier, but numbers are not clear as Netflix stopped disclosing this information in 2025.
“During the year ended December 31, 2025, we discontinued the reporting of membership numbers, including average paying memberships and average monthly revenue per paying membership.” - Netflix’s 2025 Annual Report
Nonetheless, there are reports which suggest that, despite the ad-tier offering the cheapest subscription, it may be much more profitable than the Standard Plan due to the high monetization from ads on frequent users.
As of 2025, advertisements accounted for 4% of the company’s total revenues, raking up c. $1.5 billion.
4. Industry and Market Analysis
Netflix operates in an incredibly large market, which is estimated to exceed $1.5 trillion.
Despite having originally focused on movies, series, and documentaries, the company has recently expanded into gaming and live events.
Each new service offered helping to significantly expand the company’s TAM, and opening new sources for sustainable growth.
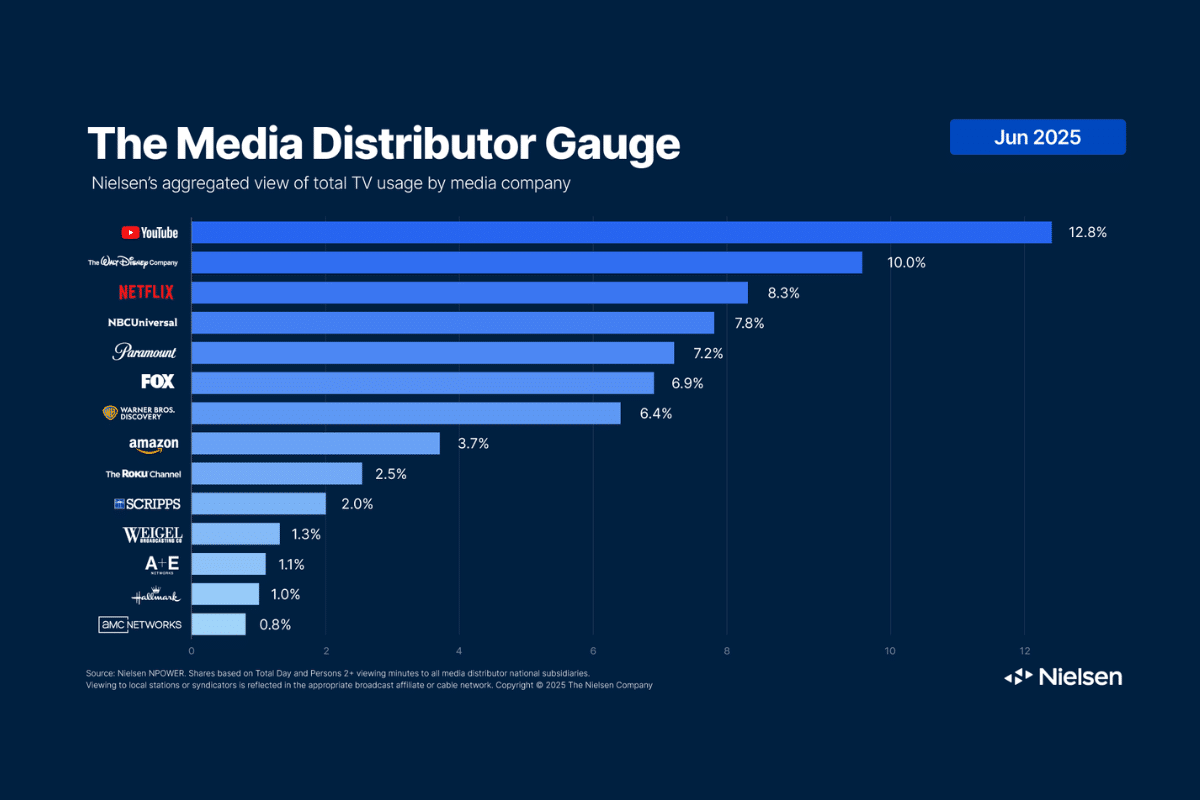
Even though Netflix is the clear leader by number of subscribers, they are not the company with the highest share of TV usage, with YouTube and Disney being ahead as of June 2025.
5. Competitive Analysis
Competition
The entertainment market had been ruled by the same legacy companies for over a century, until leaner, platform based competitors like Netflix emerged as realistic challengers.
More recently, the streaming landscape has shifted from a battle for subscribers to a battle for total entertainment time.
This allows us to group Netflix’s competition into three distinct categories:
Ecosystem giants
This category includes the companies where streaming is a small part of a larger business model such as Prime Video and Apple TV among others.
These companies pose a threat due to their massive budgets and their bundled offerings with additional benefits such as music or free shipping.
More often than not, these companies offer these services to increase the perceived value of their other segments, with Amazon Prime being mainly focused on its marketplace.
However, as these companies are involved in many other businesses, they lack the ability that Netflix has on generating industry-leading content.
Despite these companies being solid competitors to Netflix by leveraging their budgets and their existing subscribers, their main disadvantage comes from them not being entirely focused on entertainment.
Legacy content
This segment consists of traditional entertainment companies like Disney+, HBO Max, or Paramount Plus.
These businesses pose a threat to Netflix as they own some of the biggest IP portfolios, including Star Wars, Harry Potter, the Marvel Cinematic Universe, and hundreds more.
This allows these companies to have a unique advantage when developing new content, and creates a large revenue source from licensing the already existing content to other streaming platforms.
However, these companies are struggling with high debt and a poor leadership, allowing Netflix to gain market share at an outstanding pace.
The expected trend in the following years is that these businesses will lose relevance to newer platforms.
Attention rivals
This segment consists of other digital entertainment companies disrupting the traditional model, which compete for the watch time of the same user base.
Companies like YouTube and TikTok offer content for free and, through user generated content, as a direct substitute to people watching Netflix shows.
Despite these platforms being completely free and extremely asset light businesses, YouTube already generates more revenue than Netflix.
However, these companies lack the prestige and professionally made content that incentivizes customers to be willing to pay a monthly subscription, like Netflix does.
Moat and Competitive Advantage
Currently, Netflix is developing a wide moat which mainly stems from economies of scale and its intangible assets.
Netflix has managed to amass a global subscriber base of over 300 million, allowing it to spread the cost of a blockbuster across its massive audience. This allows the company to spend much less per user on movies and shows, while being able to maintain its impressive 24% net margin despite their massive content production budget.
On the other hand, Netflix has established one of the strongest and most recognizable brands in the world, leading to lower customer acquisition costs and higher retention rates. Their intellectual property also includes their original content library with franchises like Stranger Things or Squid Game. This is an incredible moat as it consists of assets which other competitors cannot replicate.
6. Bull Thesis
NFLX 0.00%↑ has fallen over 40% from its all-time highs, which it set in June 2025. However, it is a fundamentally stronger business with wider profitability margins.
The bull thesis centers on its ability to achieve achieve best-in-class shareholder returns, through three specific factors:
Stable and resilient revenue growth
Improving unit economics and margins
Massive FCF generation and return to shareholders
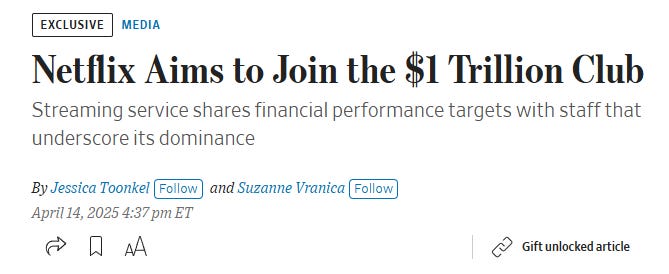
Management has established long-term targets, being very ambitious with their 2030 expectations:
Valuation: $1 trillion market cap
Revenue: $78 billion (2x increase from 2024)
Operating Income: $30 billion (3x increase from 2024)
Ad-Tier Revenue: $9 billion (4x increase from 2024)
In order to achieve the “Stable and resilient revenue growth” component, Netflix is leveraging its subscriber growth and its advertising revenue.
While I don’t expect the company to keep growing at the speed it used to, its revenue growth has become highly stable and resilient.
Due to its large size, and freed up capital that was saved for the WBD acquisition, the company will be able to spend more on content than ever before, reinforcing its Originals segment and reinforcing its own IP library.
Since the acquisition will not be taking place, I expect Netflix to use most of its FCF to conduct massive share buybacks and invest heavily into content development.
This investment will not offer a 100x return due to the company’s current size and expected growth rates, but currently Netflix has one of the most investor-friendly business models which is positioned to outperform the S&P 500 over the long term.
7. The CFC Quality Score
Netflix scored 21/22 on The Compounder Score, a framework for assessing companies’ fundamentals, which ranks it as a “Best-in-Class” business.
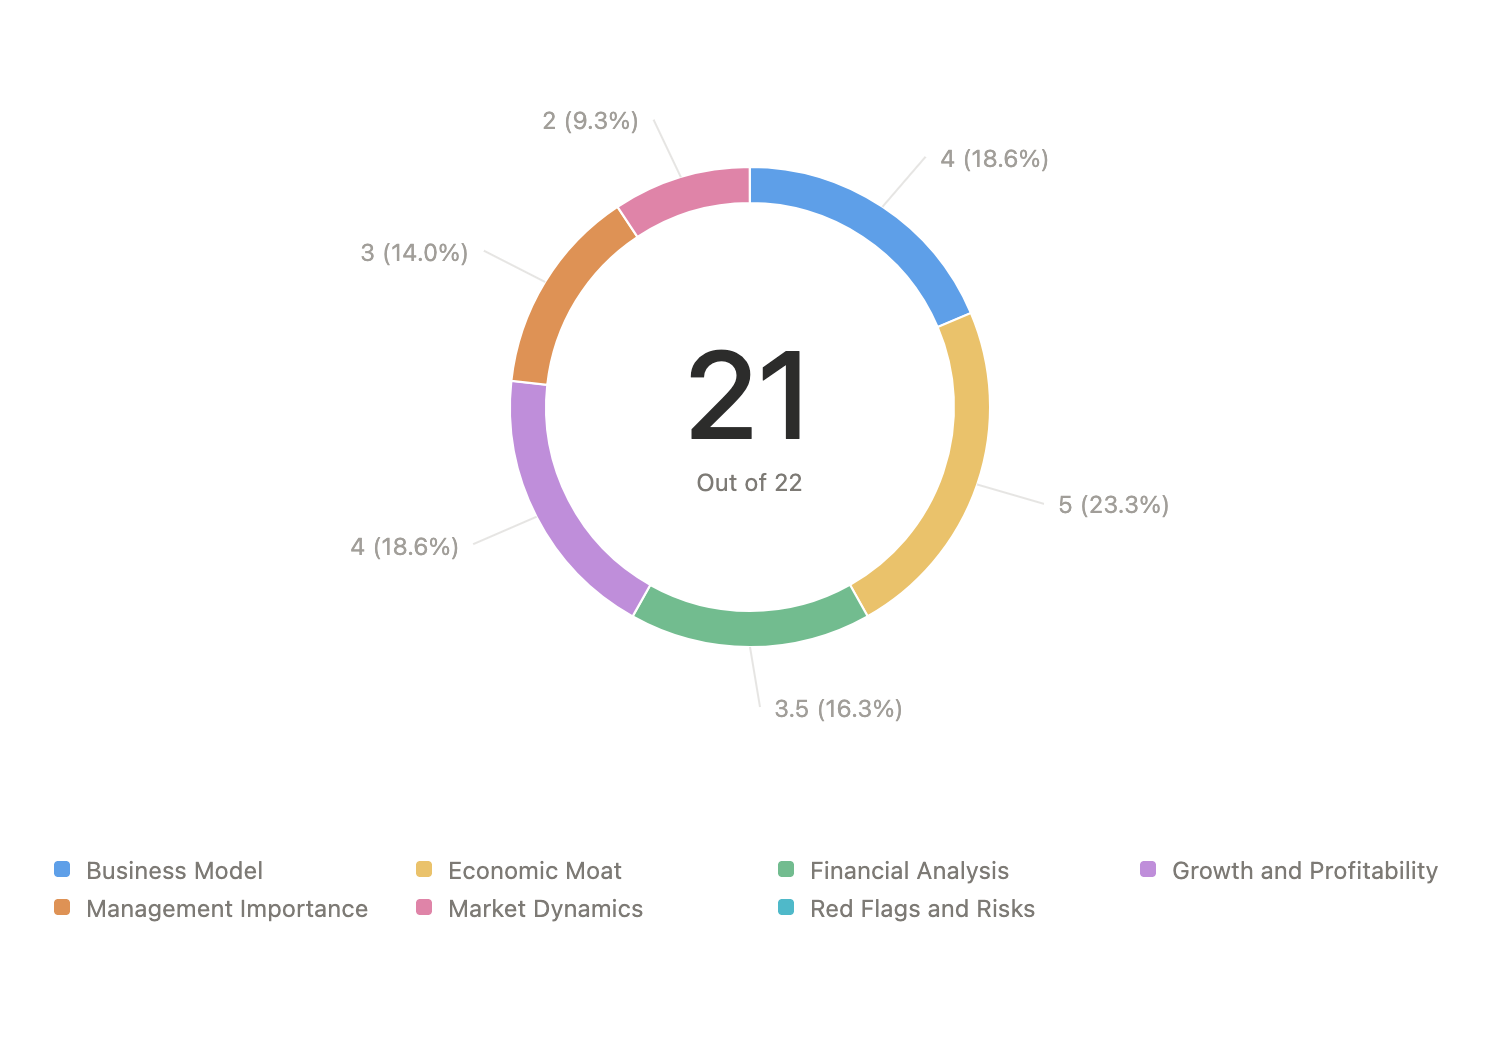
This has been the best result a company has obtained in The Compounder Score so far, ticking all the fundamental boxes except for its cyclicality and regulatory risks.
You can view the full breakdown below:
Netflix (The Compounder Score)

I applied The Compounder Score—a weighted framework for assessing companies’ fundamentals—as a preliminary screening tool to determine if Netflix ($NFLX) warrants a full deep-dive analysis.
8. Risks
Risk 1: Lack of Evergreen IP
Without owning a massive studio with a large library of evergreen IP like WBD or Disney, Netflix is stuck having to generate completely new content on a monthly basis.
This means they have to spend billions of dollars every year to make new shows to keep people from canceling.
Other streaming platforms like Disney have endless content generation opportunities due to IP like Star Wars, or the MCU, while Netflix has yet to develop these franchises that people will watch over and over again for decades.
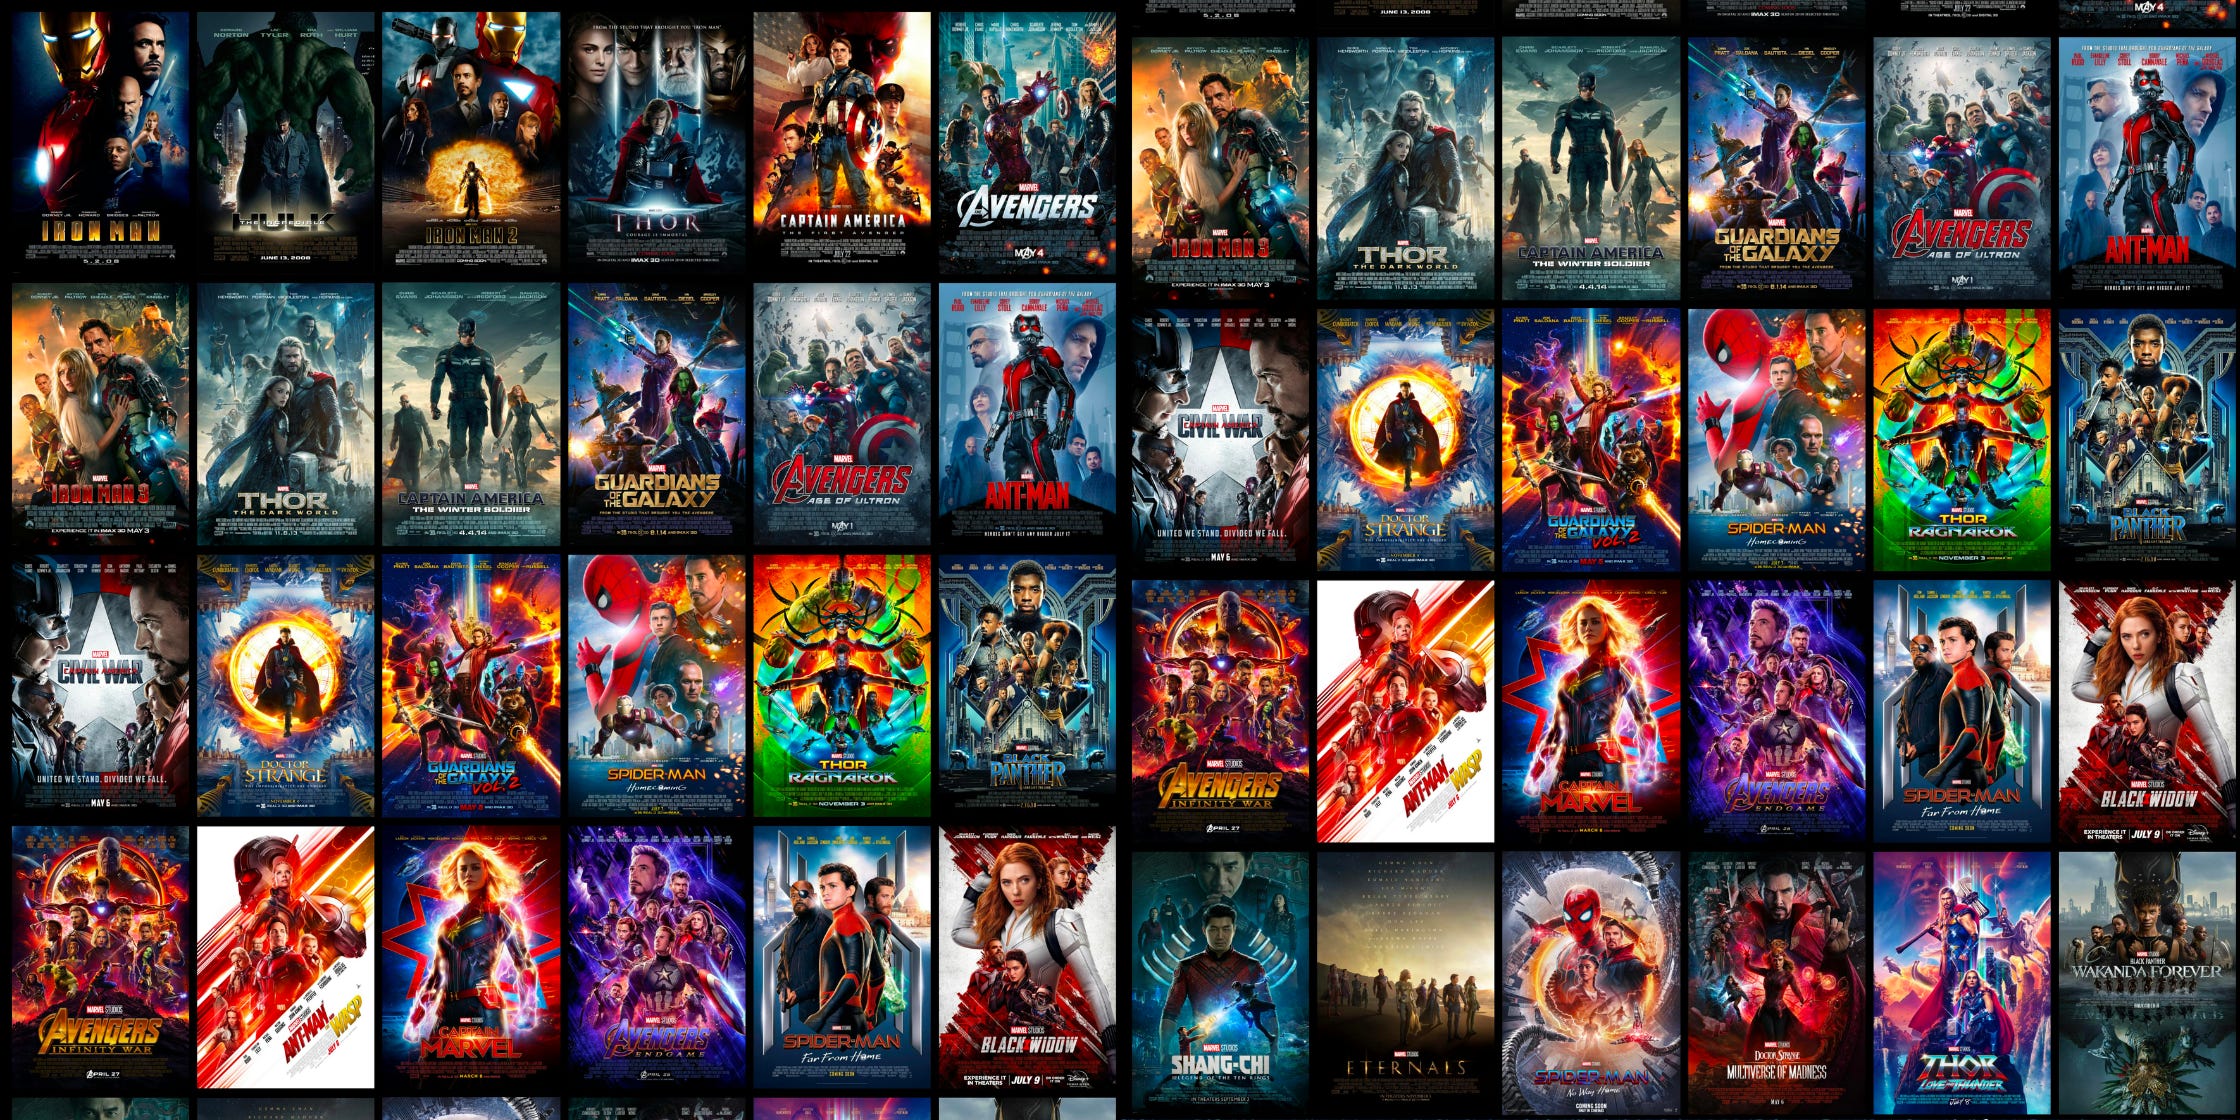
The main risk is the dependence on paying royalties to rent popular shows from other studios or invest billions into developing Originals.
If they were to have a dry spell, where they are unable to produce another hit like Squid Game or a Stranger Things, their Churn Rate could spike as users jump to other apps.
Risk 2: Increasing Competition
Netflix is a pure-play streaming company, meaning streaming is their entire business.
This is becoming a more dangerous niche to be in every year due to their largest rivals (Amazon Prime, Apple TV, and YouTube TV) not needing to make a profit on content to survive due to streaming being a small portion of their businesses.
These giants can afford to lose billions of dollars outbidding the competition for sports rights just to hurt Netflix’s business.
Since Netflix needs its streaming service to be profitable to survive, it can’t always win these bidding wars, as we have seen with the WBD deal.
If Netflix were to lose out on the best sports and movies due to not having the infinite budgets of Big Tech, it could slowly lose its crown as the #1 entertainment destination.
Risk 3: Market Saturation
Finally, Netflix may be approaching market saturation, which happens when a company has managed to sell its offering to most of its total addressable market.
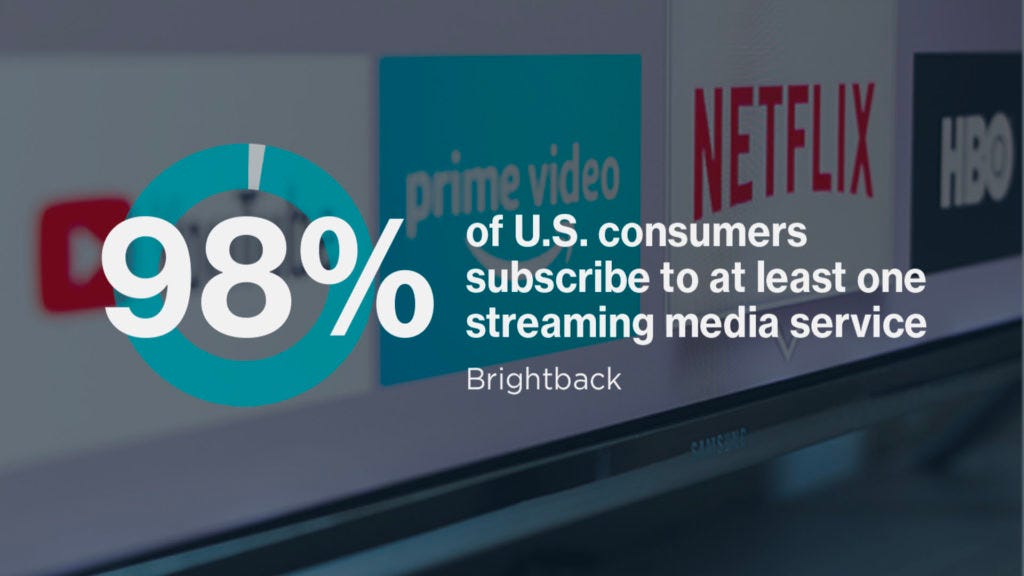
In 2026, c. 98% of U.S. households were subscribed to at least one streaming service, suggesting that growth in mature markets will mainly depend on pricing increases and stealing market share.
If their new ad-supported plan does not manage to live up to its expectations, Netflix’s growth could slow down, making the stock less attractive to investors.
9. Financials
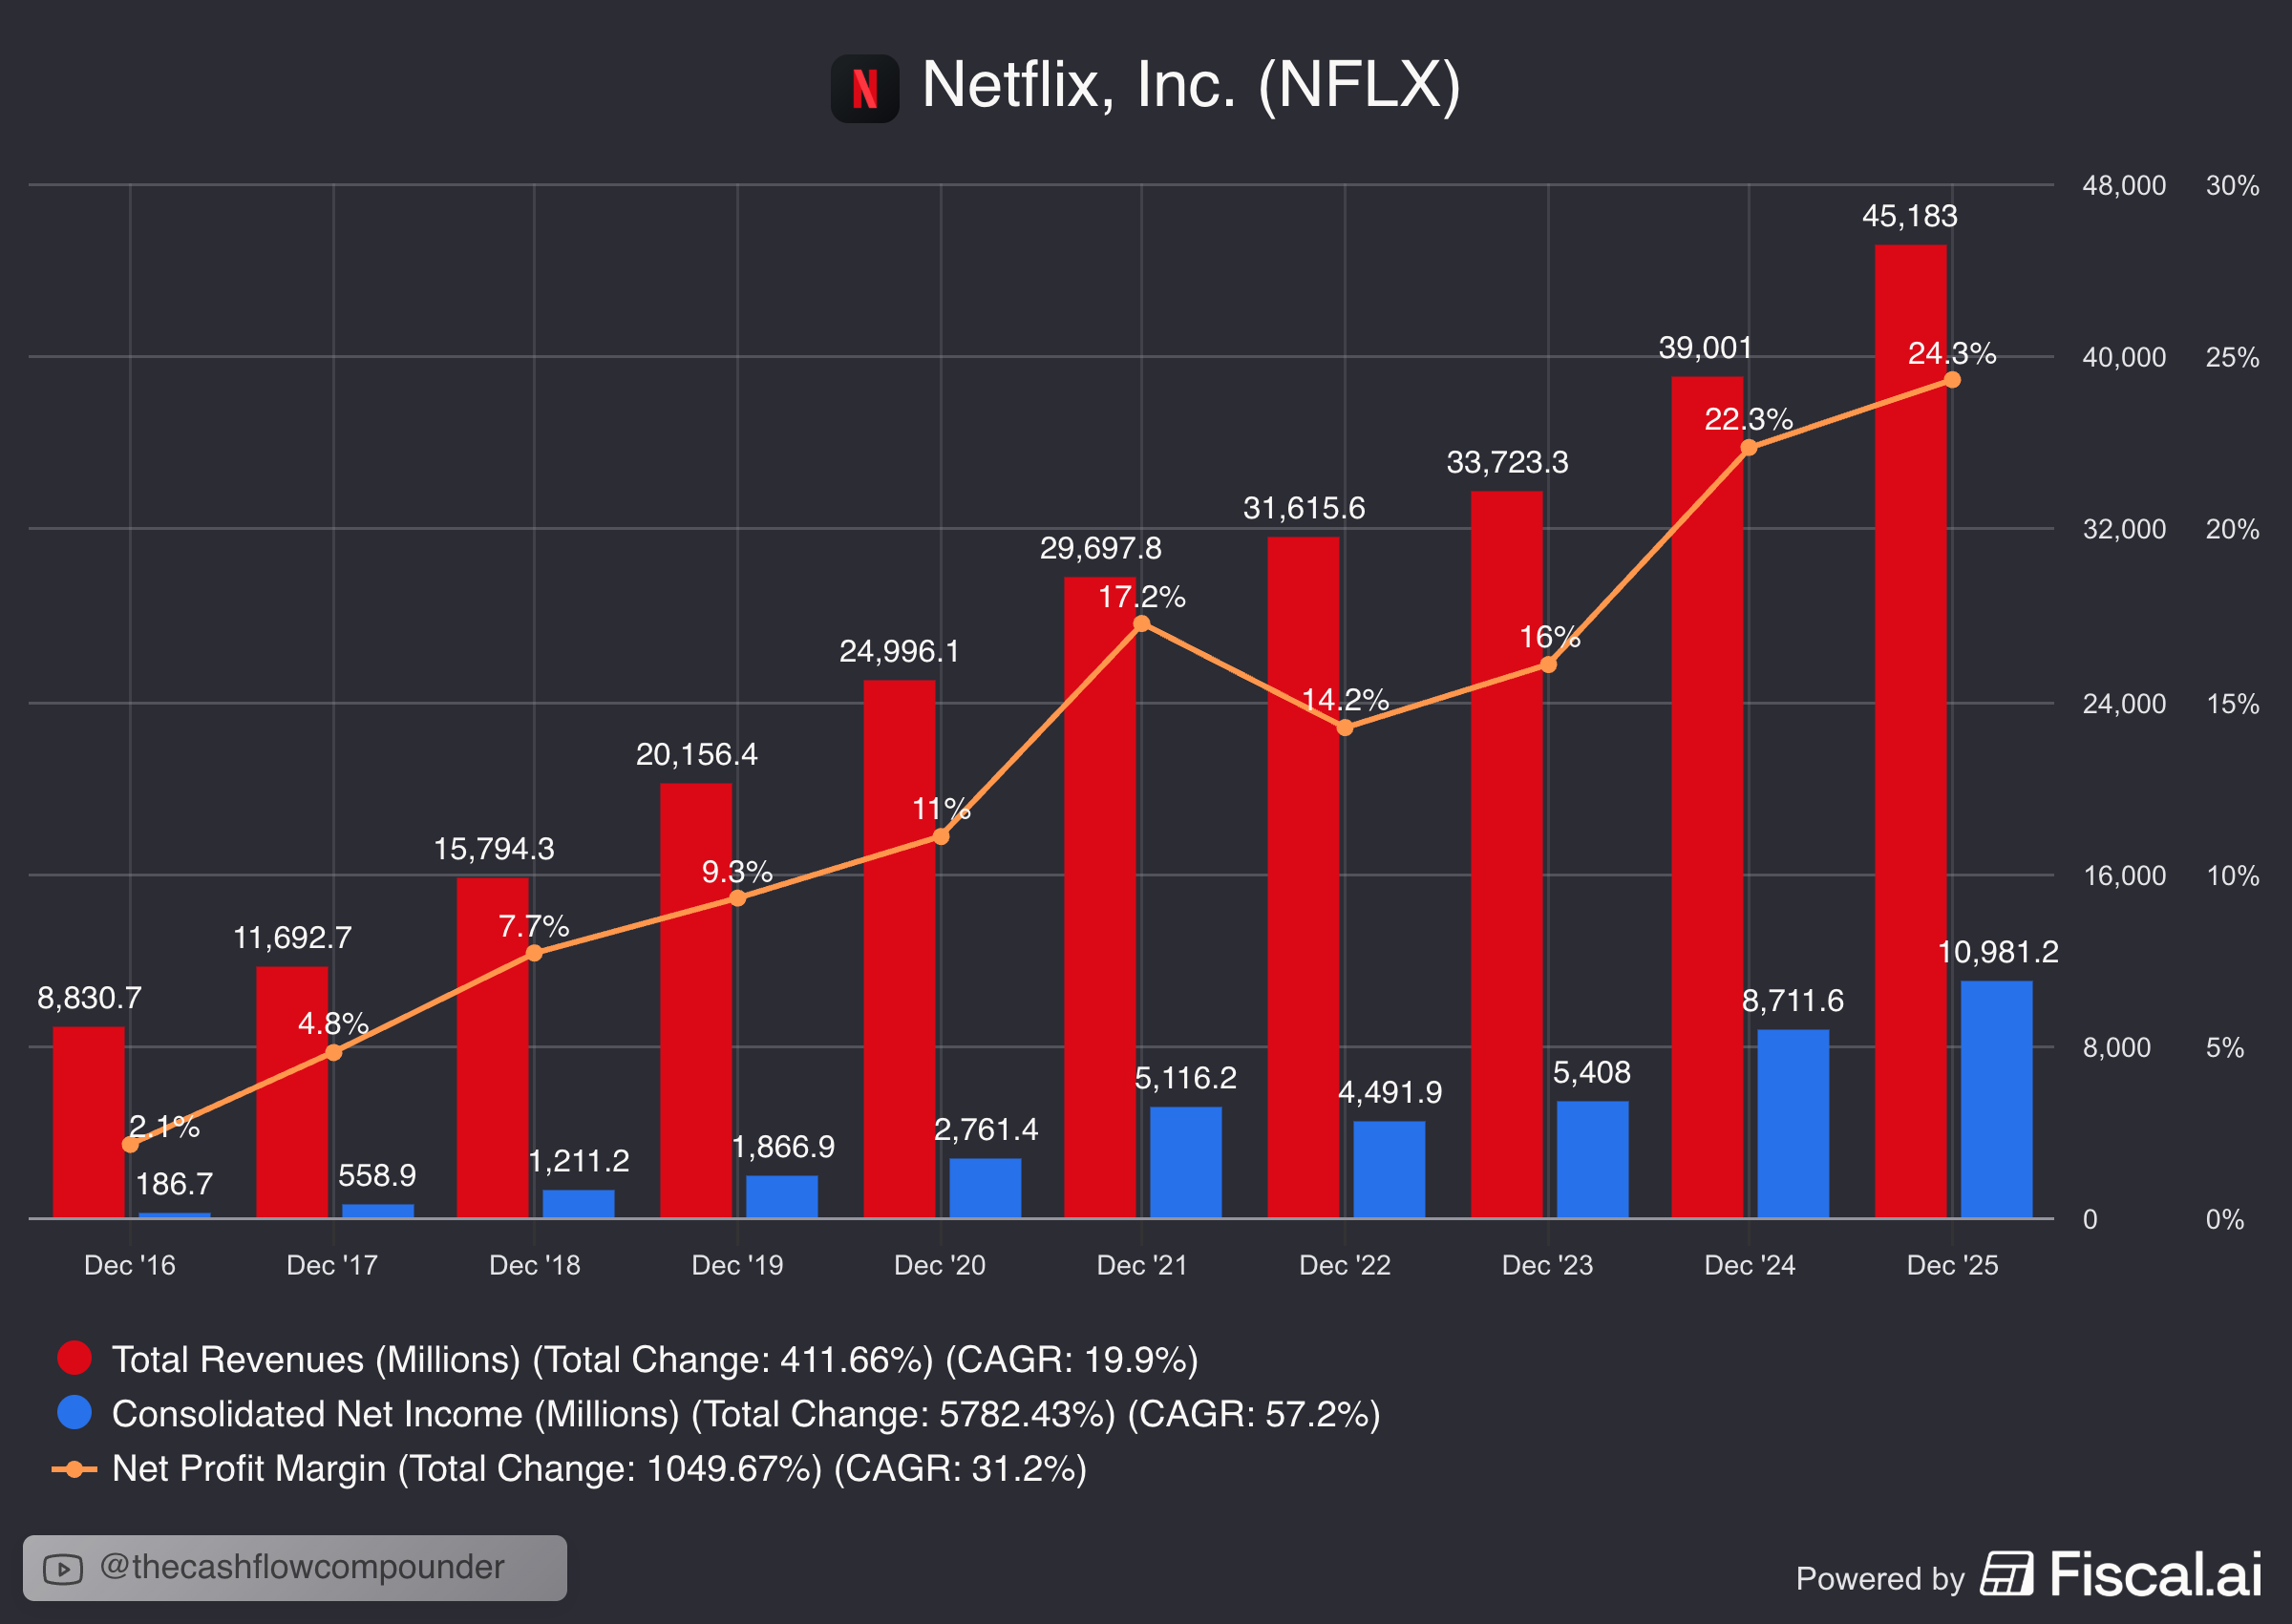
As of FY2025, Netflix reported over $45 billion in revenue, a substantial increase from the $32 billion posted in FY2022, achieving a 12% revenue growth CAGR over the past three years.
This revenue growth has been sustained by their advertising revenue, which exceeded $1.5 billion in 2025, representing c. 4% of the company’s total revenue.
This has rapidly become one of the company’s strongest growth sources, with management expecting it to double in 2026, reaching $3 billion for the full year.
Netflix’s top-line growth is translating into increased profitability due to the company’s Operating Leverage, allowing most additional revenue to flow directly into Net Income.
As a result, Netflix has been able to expand its Net Margin from -14% in FY2022 to 24% in FY2025.
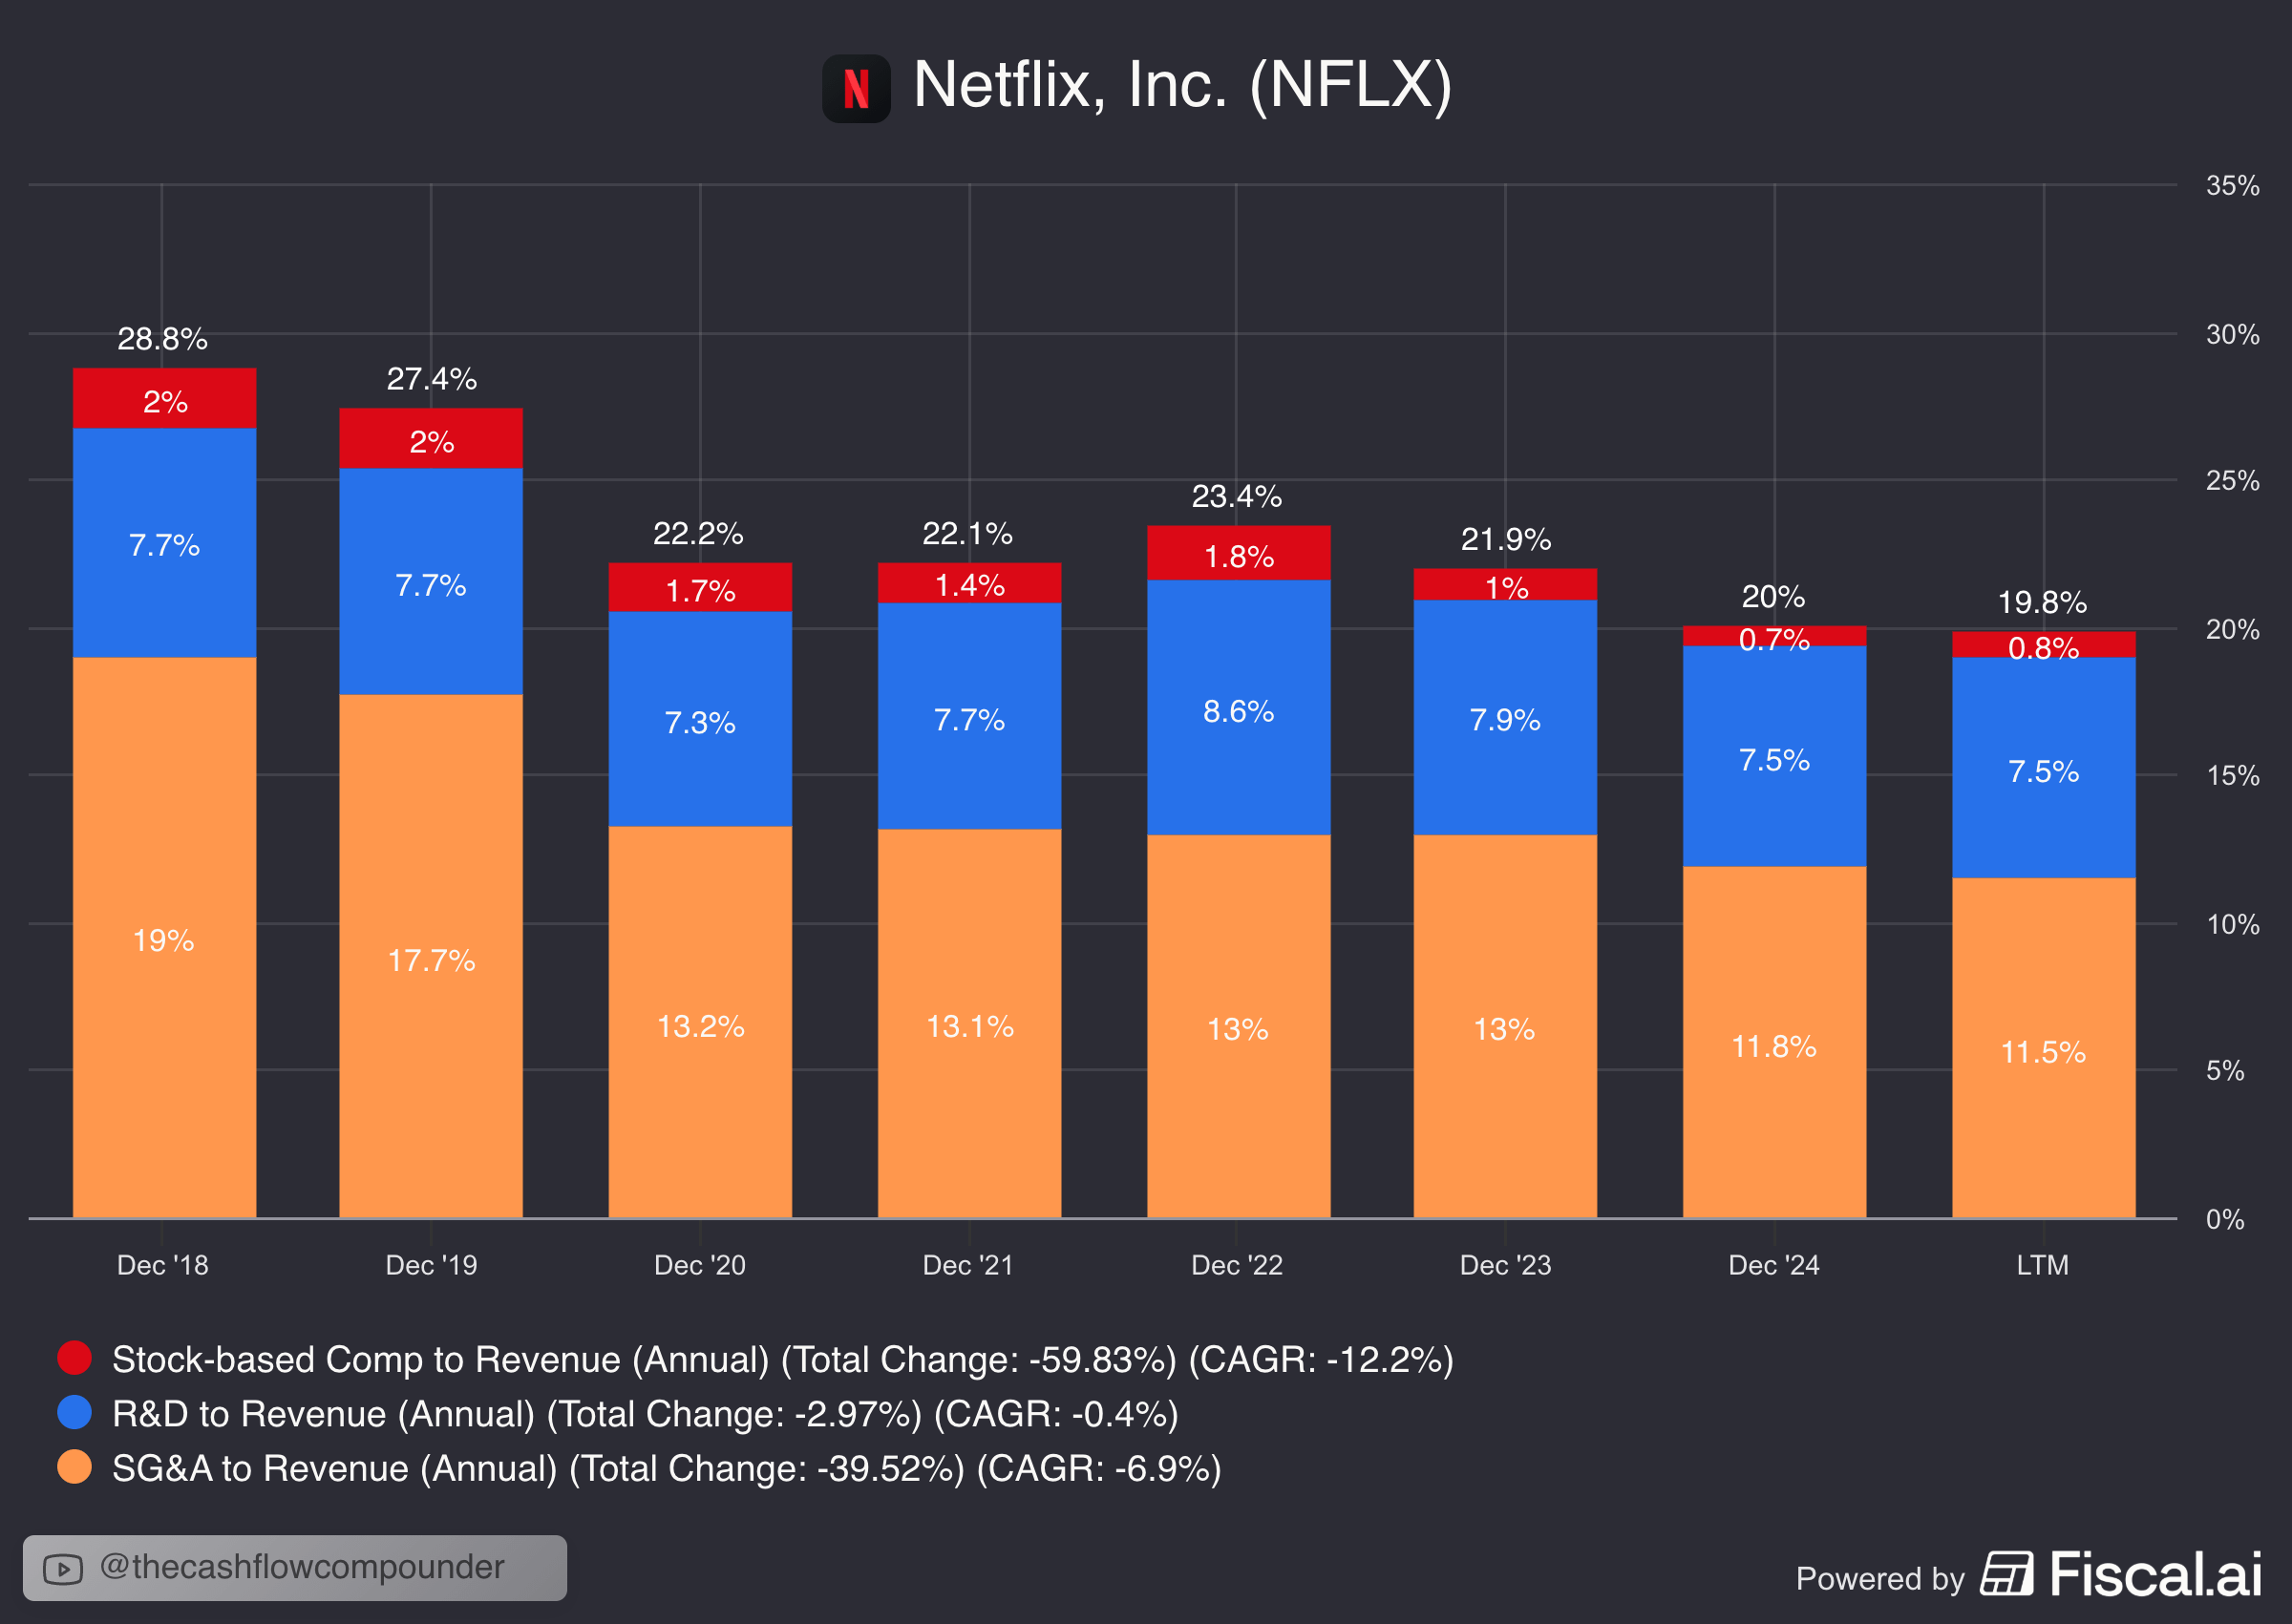
The margin expansion has largely been enabled by their stable COGS and their decreasing OPEX relative to their revenue.
This can be clearly seen by the evolution of SG&A, R&D, and SBC as a percentage of Netflix’s total revenue, which has decreased from 28.8% in 2018 to 19.8% in 2025.
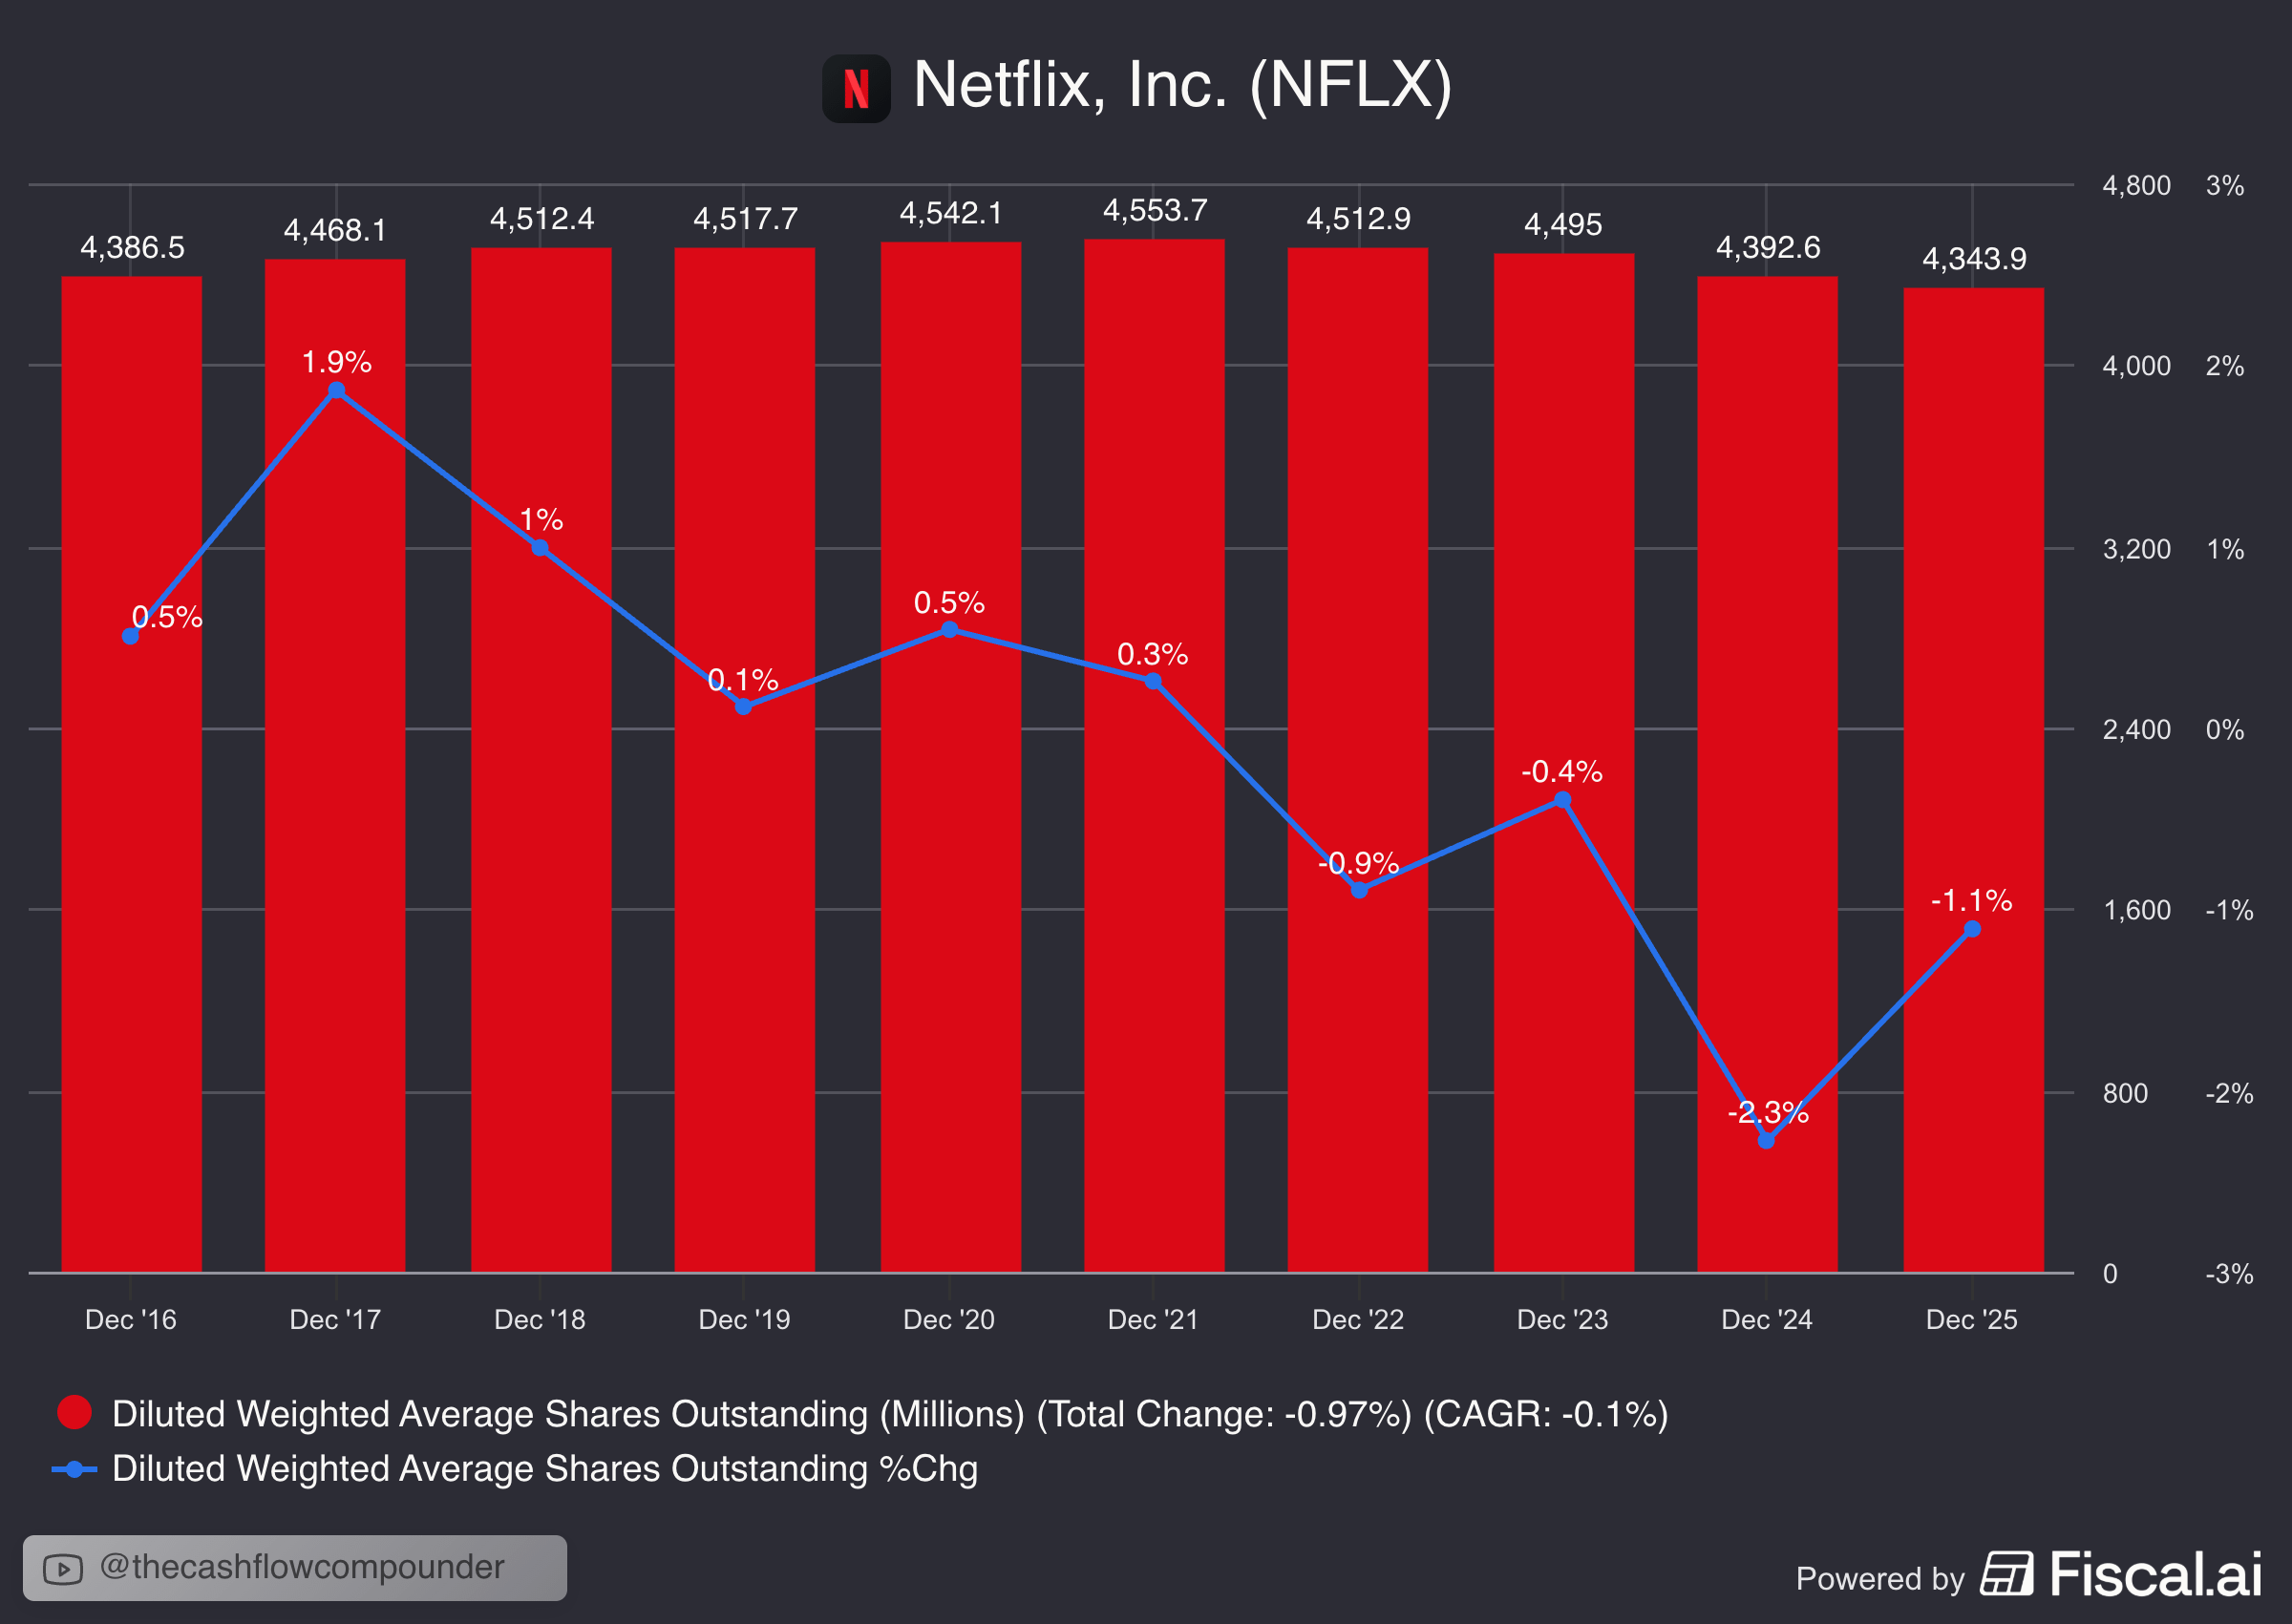
Finally, the company has become much more shareholder-friendly in the past few years, returning massive amounts of FCF mainly through share buybacks.
Through these programs, the company has been able to decrease its shares outstanding by 3.4% in 2 years.
Additionally, Netflix halted its buyback programs during the second half of 2025, to save up for WBD’s acquisition.
Since that will not be taking place, Netflix has reintroduced its buyback programs, having over $9 billion in cash and cash equivalents.
We have reviewed Netflix’s incredible business, its growing fundamentals, and the bull thesis. However, with the stock trading at a massive premium, is it a clear buy, or is the risk too high?
The final, essential sections cover:
Comparable Analysis of Netflix’s historic valuation ratios versus its peers.
The Compounder DCF with potential return and intrinsic value estimates based on scenarios.
The definitive BUY, HOLD, or SELL rating, with the KPIs to track during earnings and possible deal breakers.
This part of the analysis is reserved exclusively for our premium subscribers to reward for their amazing support.
Subscribe now to get full access to all our upcoming analyses!
